How to Find the Right Person to Sell Your House

Andi • September 8, 2020

Your guide to hiring the listing agent who can set you up for success.

Your home is where you’ve lived and loved, where you’ve laughed and cried, where you’ve huddled and snuggled. You’re the pea, your home is the pod. And you’ve been through a lot together.

Now that it’s time to put it on the market, you’re likely experiencing some sadness, plus plenty of anxiety. Because really: How often does your future depend on selling your past? If you’re a little overwhelmed, we don’t blame you.

But there’s also good news: You don’t have to go it alone. 

A listing agent has your back when it comes to the financials, like setting a listing price and marketing, staging, and making repairs to your house. He or she can also help you navigate more personal issues, such as your timeline, and what you’re hoping to achieve with the sale.  

For all of those reasons, it’s important to find an expert who is right for you and your specific situation, and who can help you get what you want. Here’s how.


Know What a Listing Agent Can Do for You

Before you start interviewing prospective agents, have a clear sense of  what you want to get out of the selling process. When so much money is on the table, it’s crucial to know what your goals are, so that you can find an agent who really speaks to them.

Then, it helps to understand what a listing agent does (other than sell your most valuable asset — no big deal).

The listing agent will: 

  • Work with you to price your home
  • Market your home (we’re talking pretty pictures, social media promo, cute staging — the works)
  • Negotiate with home buyers
  • Usher the home sale through inspection and closing

Now, let’s break all of that down . . .

Pricing your home.  This is the BIG question, right? How do I set the price? The short answer is you’ll need to trust your agent to recommend a smart listing price. 

So how can you tell whether an agent — a relative stranger to you — is choosing the best price for your home? You need to do two things:

  1. Know, generally speaking, what your property is worth . Do your own research on the prices of local comps, (but understand the  limits of online property sites). Run your info by your agent for an informed perspective. 
  2. Ask the agent for pricing information on homes he or she has recently sold.  Specifically, what the differences were between their listing prices and how much the homes ultimately sold for. 

When it comes to the agent’s pricing history, you’re looking for accuracy. Anyone could suggest a high price for your home, knowing it’s what you’d like to hear. But nobody (especially you) wants to have a house languish on the market, or to reduce a price repeatedly.

Marketing your home.  The listing agent will also get the word out that your house is on the market, using a combination of old-school (but powerful) marketing techniques — such as direct mail, signage, and open houses — and the modern methods we know and love, like social media. Savvy agents will post pics of your house on Instagram, Facebook, Twitter, and any other platform that can get likes  plus  the attention of other real estate agents who can bring buyers to the table.

Negotiating with buyers.  When offers start pouring in, your agent will negotiate with prospective buyers on not only the sale price but also on what contingencies (aka special circumstances) are attached to the contract. As with any negotiation, there could be some stressful, fraught moments with the buyers. You’ll want an agent who can step up for you, and who has a negotiation style that you’re comfortable with.

Closing the sale.  Once you’ve signed a purchase agreement with a buyer (woo-hoo!), your agent will help you navigate the sale’s remaining steps. This includes negotiating home repair requests post inspection and dealing with any last-minute surprises before closing.

The average listing agent does all of the above. A  great  listing agent does all of the above, while also inspiring your confidence — that they’re getting the best price for you, and that they’re representing you and your home in the best possible light. 

So, let’s talk about how to find and hire  that  kind of agent.


Ask These Questions to Find a Great Listing Agent

Here, time is on your side. Aim to hire a listing agent six to eight weeks — or more — before the day your house is listed on the market (also known as the “go-live date”). You’ll be grateful for the cushion, especially if the agent you ultimately hire recommends that you make repairs or upgrades to your home before it’s listed. (That wouldn’t be unusual.)

To find prospective agents, start with your network. Ask friends, relatives, neighbors, and colleagues for recommendations. Word-of-mouth endorsements, as always, can be priceless.

You can also turn to another trusted friend: the internet. Property websites such as  realtor.com®  have directories that let you search for agents in your area. These databases can clue you into important details, such as an agent’s years of experience, number of homes sold, and past client reviews.

Three out of four home sellers only contact one candidate before picking their listing agent, according to a NATIONAL ASSOCIATION OF REALTORS ®  report. While that may be the norm, it’s smarter to shop around. Interview at least three agents before deciding on the one you want to work with. 

During the interviews, ask these questions to help assess whether an agent is the right fit you:

  • Do you work as an agent full-time?  Like most professions, experience is no guarantee of skill. That said, much of real estate is learned on the job.
  • How long have you been in the business?  Generally, the more experience an agent has, the more they’re tapped into the local market. 
  • How many homes have you sold in my neighborhood in the past year?  You don’t need to find an agent who specializes only in your community, though that would be ideal. You do want someone who has recently sold at least a few homes in your neighborhood and knows the local and hyper-local inventory.
  • What’s the typical price range of homes you sell?  Most agents work across multiple price points, but you don’t want an agent who has never sold a home in your range.
  • What’s your fee?  An agent should be able to articulate their value and explain their commission rate.  
  • How will you market my home?  You don’t want to hire someone who’s just going to stick a For Sale sign in your yard and call it a day. The agent should present a comprehensive marketing plan for your listing — this should include strategies for staging your home, taking professional photographs of your home, promoting the listing on social media, marketing to other brokers, scheduling open houses, etc.
  • Will I be working with you directly, or with a team?  Some agents lead or work as part of a sales team. The lead listing agent shares client responsibilities with other agents. Where one agent may handle private showings for a listing, another may host open houses. A benefit is that for the same fee, you get many people working for you. But if you want the sole attention of the listing agent, you may want to stick to a one-on-one arrangement. 
  • Will you provide one-on-one service?  Whether you’re working with one agent or a team, ask how responsive they can be to you, your timeline, and your goals.
  • How long on average are your listings on market?   Your average sold-to-list price?  This can help you suss out whether the agent is a solid marketer and negotiator. These are real estate stats that the agent can pull from your local multiple listing service, or MLS. 

The bottom-line: It’s in your best interest to pick an agent who understands your goals, fits your personality, and can get your home sold for top dollar. When you meet someone who can offer all of the above, congratulations — you’ve found your listing agent.


First Thing: Know What You’re Signing up For

Now that you know what you’re getting when you find the right listing agent, let’s make sure you know what you’re committing to when you sign that agent’s “representation agreement.”

The most common type of representation agreement is the exclusive right-to-sell agreement — a legally binding contract that states you’re going to use that agent to sell your house. Under this agreement, you’re giving the agent (and the agent’s brokerage) the right to sell the home for a mutually agreed-upon time period and compensation. IOW: You get peace of mind that you have a dedicated agent; the agent gets peace of mind that you’re only using their services. Other common terms include the agent’s duties to you, like marketing, and a dispute resolution plan.

There are other types of representation agreements, where agents don’t have exclusive rights to sell the property — meaning multiple agents can try to sell the home and compete for the commission. However, when agents know a listing is exclusively theirs, they’re fully invested in selling the property (which, again, should also give you peace of mind).

Every contract has an expiration date, but the length of the contract can vary. Some are three-months; others six months. It all depends on what you and the agent agree upon. If the contract expires before your house is sold, you can re-list your home with another agent. 

Of course, there’s a chance you sign an exclusive listing agreement but just aren’t satisfied with the job your agent is doing. To protect yourself, make sure the representation agreement has a cancellation or termination clause that lets you void the contract before the expiration date without any financial penalty.


Understand How a Listing Agent Gets Paid

So  . . . at the end of the day, how do listing agents get compensated for their work? 

Real estate commissions — including the listing agent’s commission — are typically charged as a percentage of the home’s sales price. For example, on a $300,000 house, a 6% commission would cost $18,000. Commissions are negotiable. The commission is usually split between the listing agent and the buyer’s agent as well as their respective brokers. 

A caveat: If an agent represents the seller  and  the buyer, the agent becomes a dual agent and earns both sides of the commission. In dual agency, you may have more room to negotiate the rate — just keep in mind that you’re not being represented exclusively as you are in single agency. You may want to hire an attorney to review documents and help you negotiate.

The listing agent’s commission fee often covers the cost of professional photos, marketing and marketing materials, and any administrative fees charged by the agent’s brokerage. 

Also, consider this: Great agents — with their pretty photography, HGTV-worthy staging tricks, and marketing smarts — earn their keep. 

So, if you’ve read all of the above, you’ve done your homework to find a great agent. Now you’re ready to sell that house.
HOUSELOGIC

HouseLogic helps consumers make smart, confident decisions about all aspects of home ownership. Made possible by REALTORS®, the site helps owners get the most value and enjoyment from their existing home and helps buyers and sellers make the best deal possible. 

By Andi Dyer • September 11, 2026
I recently had the opportunity to represent the buyer on this Blaine home, and it’s a good time to look at what’s happening in the 98230 market. August numbers show a market giving buyers a little more breathing room: • 184 homes for sale, up 17.2% from last year • 5.9 months of inventory, up from 5.2 months • Homes that sold took 73 days on market, compared with 32 days last August • The median sales price was $569,950, up 3.6% What does that mean for buyers? More choices, more time to evaluate a property, and potentially more room to negotiate, depending on the home. But it’s not a bargain-bin market. Blaine prices are holding relatively steady, so understanding the individual property, its competition, and the seller’s position still matters. 𝗠𝗼𝗿𝗲 𝗶𝗻𝘃𝗲𝗻𝘁𝗼𝗿𝘆 𝗰𝗿𝗲𝗮𝘁𝗲𝘀 𝗼𝗽𝗽𝗼𝗿𝘁𝘂𝗻𝗶𝘁𝘆. 𝗚𝗼𝗼𝗱 𝘀𝘁𝗿𝗮𝘁𝗲𝗴𝘆 𝗵𝗲𝗹𝗽𝘀 𝘆𝗼𝘂 𝘂𝘀𝗲 𝗶𝘁.
By Andi Dyer • August 28, 2026
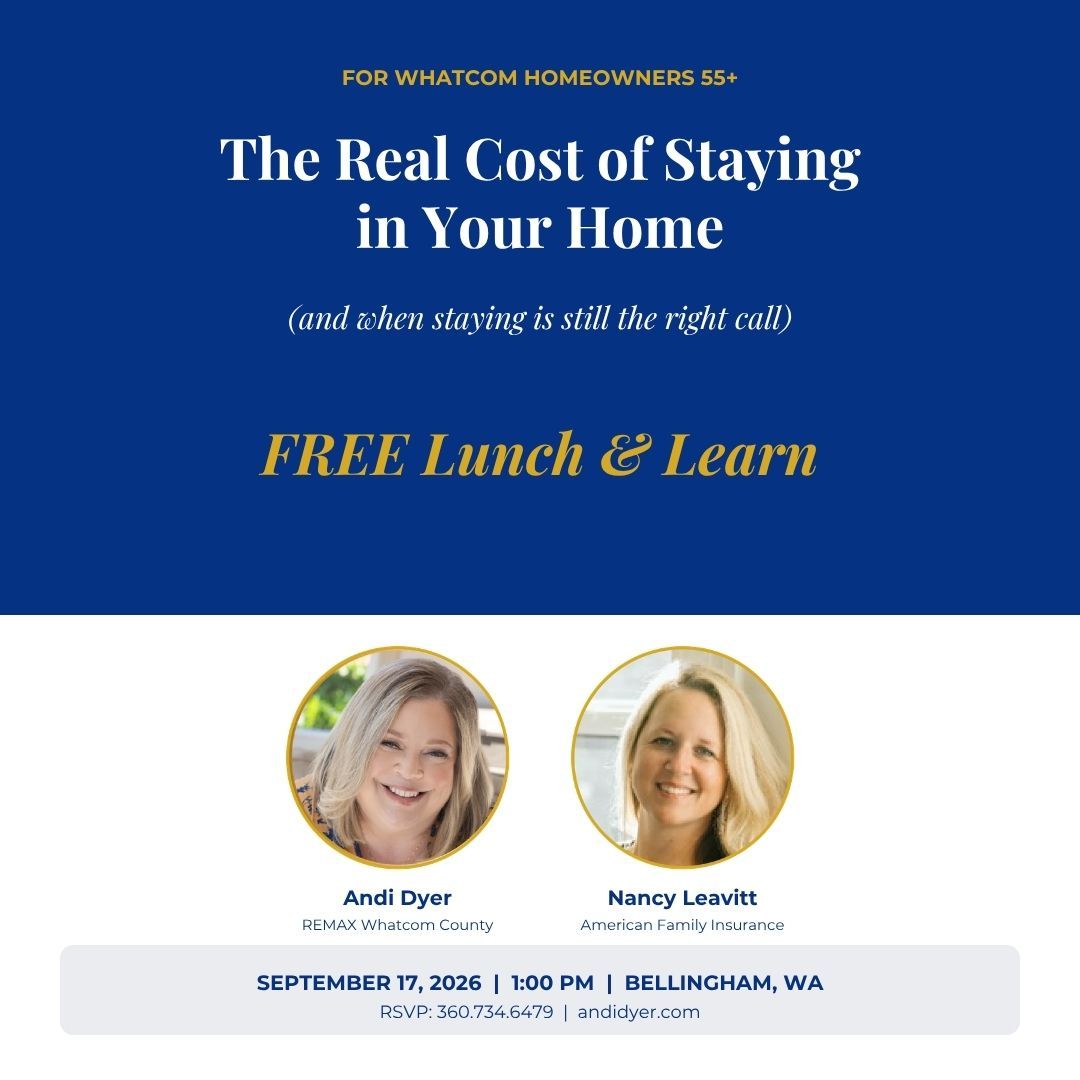
 Deciding whether to sell your home, downsize, or stay where you are comes down to more than your home's value. For Whatcom County homeowners, the right decision should consider your equity, monthly housing costs, maintenance, insurance, accessibility, lifestyle, and what it would actually cost to move. Sometimes selling and right-sizing makes sense. Sometimes staying in your current home is the better financial decision. The important thing is knowing the numbers before you decide. Should I Sell My Home or Stay? If you're wondering whether it's time to sell your home, start with one question: Does my home still fit the way I live today? A home that was perfect 10 or 20 years ago may now have unused bedrooms, stairs you don't enjoy, a large yard to maintain, or repairs you would rather not tackle. On the other hand, a home that's paid off or has a low mortgage payment can be difficult to replace affordably. That's why I encourage homeowners to look at the entire picture before assuming downsizing will save money. Is It Cheaper to Stay in Your Home or Downsize? Not necessarily. A smaller home can reduce utilities, maintenance and property upkeep, but moving comes with its own costs. A replacement home may have a higher price per square foot, HOA dues, increased property taxes or a new mortgage at today's interest rates. When comparing staying versus selling, consider: Mortgage payment and remaining loan balance Property taxes Homeowner's insurance Utilities Landscaping and property maintenance Upcoming repairs or renovations HOA dues at a potential replacement property Cost of buying or renting your next home Moving and selling expenses Your estimated proceeds and available equity after a sale The better question isn't simply, "Would a smaller house cost less?" It's "Which housing choice makes the most financial and practical sense for the next stage of my life?" What Does Right-Sizing Your Home Mean? Right-sizing means choosing a home that fits your current lifestyle, rather than simply moving into a smaller house. For some homeowners, that means fewer bedrooms and less yard work. For others, it might mean one-level living, a primary bedroom on the main floor, fewer stairs, better accessibility, or living closer to family, medical care, shopping and friends. And sometimes right-sizing means staying exactly where you are and making your current home easier to live in. Is Aging in Place a Better Option? For many Bellingham and Whatcom County homeowners, aging in place can be an excellent option if the home can safely and affordably meet their long-term needs. Consider whether your current home has: A bedroom and full bathroom on the main level Manageable stairs and entryways A reasonable amount of property to maintain Access to transportation, shopping and healthcare Space that could be modified for future accessibility Maintenance and repair costs that fit comfortably within your budget You may find that a few thoughtful improvements make staying in your home far more practical than moving. How Much Is My Whatcom County Home Worth? Knowing your home's current market value is one of the most important pieces of the stay-or-sell decision. Your estimated equity can help determine what choices are realistically available to you. Online home-value estimates are a useful starting point, but they may not accurately account for your home's condition, renovations, neighborhood, view, acreage, outbuildings or other features that affect buyer demand. A local real estate market analysis can provide a more detailed estimate based on recent comparable sales and current competition in the Bellingham and Whatcom County real estate market . And getting that information doesn't mean you've decided to sell. Sometimes knowing what your home is worth gives you the information you need to confidently decide not to sell. What Should I Consider Before Downsizing? Before putting your home on the market, ask yourself these questions: 1. What would I realistically net from selling my home? Your home's sale price and the amount you walk away with are two different numbers. Consider your mortgage balance, selling expenses and other potential costs. 2. What will my next home cost? Look at actual homes that meet your needs rather than assuming smaller automatically means cheaper. 3. Will moving improve my daily life? Consider maintenance, stairs, location, accessibility, transportation and proximity to the people and activities important to you. 4. Are major home expenses coming? A roof, siding, heating system, septic system or other major project can change the financial comparison. 5. Could I modify my current home instead? Sometimes remodeling a bathroom, improving accessibility or hiring help with landscaping costs considerably less than moving. Should I Review My Homeowner's Insurance Before Deciding? Yes. Even if you aren't planning to sell, periodically reviewing your homeowner's insurance is worthwhile. Home values, construction costs and personal circumstances change. A policy you've carried for years may no longer reflect the cost of rebuilding your home or the coverage you actually need. An insurance professional can help identify whether you're adequately insured, potentially over-insured in certain areas, or missing coverage you assumed you had. When Is the Right Time to Sell a Home in Whatcom County? There isn't one perfect age, season or life event that tells you it's time to sell. The right time is when your finances, home, lifestyle and future plans point in the same direction. For some Whatcom County homeowners, selling creates greater financial flexibility and a simpler lifestyle. For others, staying in a familiar home and community provides greater value than moving. Neither decision is inherently better. A good real estate professional should help you understand both options, not convince you that selling is automatically the answer. Frequently Asked Questions About Staying, Selling and Right-Sizing Is downsizing always cheaper? No. Smaller homes can have lower maintenance and utility costs, but purchase price, interest rates, HOA dues, property taxes and moving expenses can offset those savings. Compare the total cost of both choices. What is the difference between downsizing and right-sizing? Downsizing focuses primarily on moving to a smaller property. Right-sizing focuses on finding a home that better fits your lifestyle, finances and future needs. That home isn't necessarily smaller. Should I get a home valuation even if I'm not ready to sell? Yes. Knowing your approximate home value and equity can be useful for retirement planning, estate planning and evaluating future housing options. Requesting a market analysis does not obligate you to sell. Can I stay in my home as I get older? Many homeowners can. The answer depends on the home's layout, accessibility, maintenance requirements, location and your financial circumstances. Sometimes relatively modest improvements can make aging in place more practical. How do I decide whether to sell my home in Whatcom County? Start by comparing your current housing costs and future maintenance needs with your estimated home equity and the actual cost of your next housing option. Then consider lifestyle factors such as accessibility, location, family and how you want to spend your time. Free Bellingham Lunch & Learn: The Real Cost of Staying in Your Home If you're thinking about these questions, I'm hosting a free educational Lunch & Learn with Nancy Leavitt of American Family Insurance : The Real Cost of Staying in Your Home And when staying is still the right call Thursday, September 17, 2026 | 1:00–2:00 p.m. 913 Lakeway Dr, Bellingham, WA We'll discuss how to evaluate staying versus right-sizing, how to understand your home's current value in the Whatcom County market, and why your homeowner's insurance deserves another look. Lunch is complimentary. Seating is limited so we can keep the group small and leave plenty of time for questions. Call or text Andi Dyer at 360.734.6479 to reserve your seat. Need Help Deciding Whether to Stay or Sell? You don't need to be ready to list your home to start planning. I can help you understand your home's potential market value, estimated equity and what comparable replacement homes are selling for around Whatcom County. From there, you can make the decision that works best for you. Andi Dyer Managing Broker, REALTOR® | Seniors Real Estate Specialist RE/MAX Whatcom County 360.734.6479 | andi@andidyer.com | andidyer.com
By Andi Dyer • July 30, 2026
Moving is hard for anyone. But for older adults, the process of leaving a long-time home carries a weight that goes far beyond boxes and logistics. It's a life event wrapped in memory, identity, and uncertainty, and it deserves to be handled with the care those things require. As a Senior Real Estate Specialist (SRES) with Andi Dyer Real Estate, I've had the privilege of walking alongside older adults and their families during some of life's most significant moments. And one of the most valuable partnerships I've built for my clients is with Jessica Lucey-Brzoza of Smooth Transitions NW Washington . Together, we cover the full picture, from the real estate side of the move to every logistical and emotional detail in between. Two Areas of Expertise, One Seamless Experience My role as an SRES means I'm trained to understand the unique needs, concerns, and goals of older adult buyers and sellers. Whether it's timing a sale around a move to a senior community, navigating the emotional complexity of selling a family home, or helping adult children coordinate from a distance, I bring specialized knowledge to every transaction. What I can't do, but what Jessica does beautifully, is manage everything that happens around the move itself. Jessica Lucey-Brzoza is a certified Senior Move Manager serving Whatcom and Skagit Counties. Her path to this work was deeply personal: after caring for her grandparents through the end of her grandfather's life, she went on to earn an interdisciplinary degree in somatic psychology: aging, death, and dying from Western Washington University, and trained as a death doula and massage therapist. She brings all of that to every client she serves: the knowledge, the compassion, the patience. "I approach each move as a unique and deeply human process," she says. "My style is rooted in listening, not pushing, meeting people where they are, honoring their agency, and helping them let go of items and spaces with care." That philosophy aligns perfectly with how I try to show up for my clients too. What Jessica Handles While I focus on the real estate transaction, Jessica coordinates the countless moving parts that make the actual move possible. Downsizing and Decluttering: Sorting through a lifetime of belongings thoughtfully and at a pace that feels manageable. Starting early means better decisions and less stress on move day. Relocation and Resettling: Establishing timelines, coordinating movers, overseeing packing and unpacking, and making sure the new home feels settled and welcoming from day one. Whole House Cleanout: When a family home needs to be cleared after a move or a loss, Jessica creates a custom plan, including working with Maxsold, an online auction platform, to help rehome items with care. Estate Dispersal Coordination: Working with families, attorneys, and trust officers to organize and distribute an estate when a loved one has passed. Helping Aging Parents Relocate: Navigating difficult family conversations and reducing anxiety for everyone involved by providing steady, experienced guidance. Why This Partnership Matters for You When an older adult is ready to sell their home, the real estate transaction is just one piece of a much larger puzzle. Clients often know they need to move, but the sheer volume of decisions and tasks involved can bring the whole process to a halt before it even begins. Having Jessica and me working together means my clients have a trusted team from the very start. I can introduce her early in the process, before the house is listed, so decluttering and downsizing happen on a timeline that works, not in a panic. And when the sale closes, Jessica's support continues, helping clients truly land in their new home rather than just arriving in it. Life isn't cookie cutter, and neither are our services. But our shared commitment to older adults in the Bellingham area means you don't have to figure this out alone. Ready to Talk? Whether you're thinking about selling, already in the process, or helping an aging parent navigate a transition, I'd love to connect, and I'm happy to introduce you to Jessica as part of that conversation. Andi Dyer Real Estate Senior Real Estate Specialist (SRES) andi@andidyer.com Smooth Transitions NW Washington Jessica Lucey-Brzoza, Senior Move Manager 360-927-3448 info@smoothtransitionsnww.com Bellingham, WA Serving Whatcom and Skagit Counties Schedule a free consultation with Jessica
By Andi Dyer • July 30, 2026
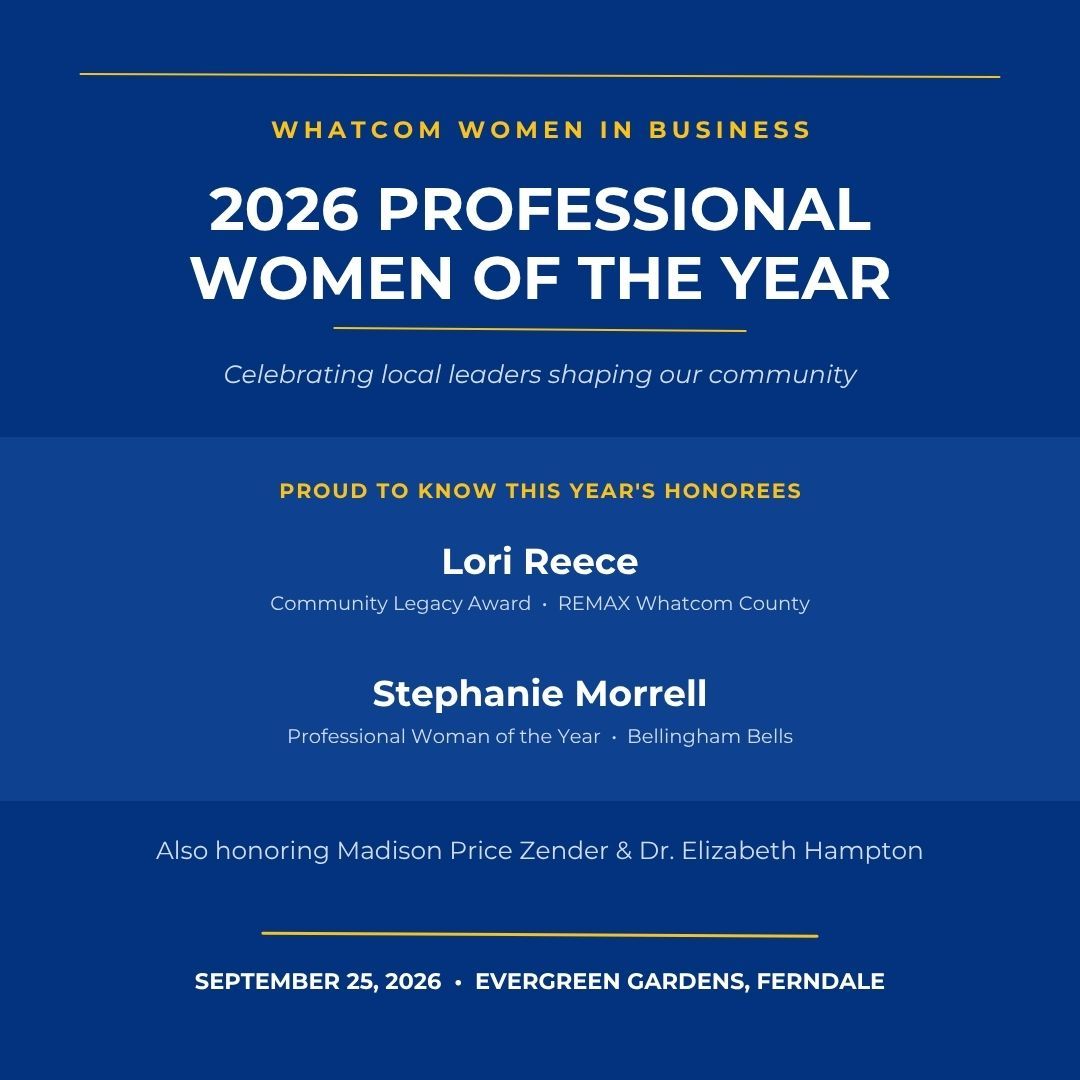
Quick answer: Whatcom Women in Business (WWiB) is honoring four local leaders at its 2026 Professional Women of the Year (PWOTY) Awards on Friday, September 25, 2026, from 5:30–8 p.m. at Evergreen Gardens in Ferndale: Stephanie Morrell (Bellingham Bells), Madison Price Zender (VSH CPAs), Dr. Elizabeth Hampton (CorePhysio), and Lori Reece (REMAX Whatcom County), who is receiving the Community Legacy Award. Tickets are available at wwib.org . Every September, WWiB honors local women whose leadership has shaped businesses and community life across Whatcom County. This year, two of the honorees are women I have the privilege of knowing personally — and their stories are worth sharing in full. Who won the 2026 Whatcom Women in Business PWOTY Awards? Four women are being recognized this year: Stephanie Morrell, Madison Price Zender, and Dr. Elizabeth Hampton as Professional Women of the Year, and Lori Reece as recipient of the Community Legacy Award. Lori Reece — Community Legacy Award Lori Reece, Broker/Owner of REMAX Whatcom County and REMAX Gateway, is receiving WWiB's Community Legacy Award this year — a distinction reserved for someone who hasn't just built a career, but shaped an entire industry. Lori founded her brokerage in 1991 with four brokers. Today it supports more than 125 real estate professionals across six offices in Northwest Washington, and she's been named RE/MAX Pacific Northwest Broker/Owner of the Year twice. Lori is my designated broker, and I see firsthand what that kind of legacy actually looks like day to day — the standard she sets, the mentorship she gives freely, and the culture she's built that so many of us in this industry get to work inside of. This award is well earned. Stephanie Morrell — Professional Woman of the Year Stephanie Morrell, President & GM of the Bellingham Bells, is being honored for a career that speaks for itself. She joined the Bells in 2013, was named the team's first female General Manager in 2016, and stepped into the President & GM role in 2024 — a tenure that has included tripling team revenue and earning two West Coast League Executive of the Year honors. I got to know Stephanie through Leadership Whatcom, and watching her lead our cohort with that same clarity, drive, and follow-through made it no surprise to see her recognized at this level. Madison Price Zender — Professional Woman of the Year Madison Price Zender is a Rising Partner at VSH CPAs, where she's built her career helping Whatcom County business owners grow and manage their finances. Her recognition reflects the trust local business owners place in her guidance year after year. Dr. Elizabeth Hampton — Professional Woman of the Year Dr. Elizabeth Hampton, a physical therapist in practice since 1987, founded CorePhysio and has led it as CEO and Clinic Director ever since, building one of the region's go-to practices for recovery and active living. Why This Matters It means something to watch people you know — people whose work ethic and character you've experienced up close — be recognized publicly for exactly those qualities. If you've crossed paths with Lori, Stephanie, Madison, or Dr. Hampton through real estate, the Bells, Leadership Whatcom, VSH CPAs, CorePhysio, or anywhere else in this community, I'd encourage you to join in celebrating them this September. Event details: Whatcom Women in Business — 2026 Professional Women of the Year Awards Friday, September 25, 2026, 5:30–8 p.m. Evergreen Gardens, Ferndale Tickets and sponsorship: wwib.org Proceeds support WWiB's mission of advancing women in business across Whatcom County, including its scholarship program for local women pursuing higher education. Source: WhatcomTalk, "Whatcom Women in Business to Honor Four Local Leaders at 2026 Professional Women of the Year Awards" About the Author Andi Dyer is a real estate agent with REMAX Whatcom County, serving buyers and sellers across Bellingham, Ferndale, and greater Whatcom County. Have a real estate question or thinking about your next move? Reach out at andi (at) andidyer.com. REMAX Whatcom County | Equal Housing Opportunity
By Andi Dyer • June 30, 2026
 A Whatcom County real estate story about persistence, creativity, and one very magical piece of land Some clients come to me with a clear picture of what they want. This client was one of them — and what he wanted wasn't a bigger kitchen or a better commute. He wanted land. He was living in a 4-bedroom condo in Sumas. Nice place, honestly — vaulted ceilings, large windows, over 1,500 square feet. By most standards, a great home. But he was done with condo life. He missed having dirt between his fingers. He wanted space for his grandkids to run around, somewhere to store his boat and kayak, and the kind of quiet that doesn't exist when you share walls. So we started looking. We Found Something Magical It didn't take long to find the right property — a piece of land on California Trail that stopped us both in our tracks. It borders a slough. Most people drive right past that slough without a second thought, but if you know what to look for, you know how rare it is. Eagles fish there — not occasionally, but regularly. You can watch them pluck salmon right out of the water. Herons show up every single day. The property backs up to a park and has only one neighbor. It's the kind of place that makes you exhale the moment you step onto it. This was the one. The Catch Here's where it got complicated. To make an offer on the California Trail property, my client needed to sell his Sumas condo first. He couldn't carry two properties, so we'd have to make the offer contingent on the condo sale. That's a real ask of any seller — essentially saying, "We want this property, but only if everything else goes right first." We got the contingency accepted. Now we just had to sell the condo. Sumas is not the fastest-moving market in Whatcom County. We knew going in that we'd need to be strategic. We priced it competitively and started hosting open houses. Then the atmospheric flooding hit. If you were in Whatcom County during those events, you know how bad it was. Most of Sumas was underwater. And even after the waters receded, the psychological damage to the market lasted much longer. Buyers were scared. The words "Sumas" and "flooding" were now permanently linked in people's minds, and that fear was showing up at every showing — or rather, in the absence of showings. A Problem Stacked on a Problem The other challenge: the condo's price point was squarely in first-time homebuyer territory. That's not a bad thing — first-time buyers are motivated, they're excited, they want to own. But many of them hit the same wall: they don't have enough for a down payment. This is where I was able to do something most agents can't. I'm certified by the Washington State Housing Finance Commission to teach the First Time Homebuyer Class. Completing that class is one of the requirements to qualify for down payment assistance programs — and there are real programs in Washington that can provide thousands of dollars in free down payment funds to qualifying buyers. So I set up multiple classes. The goal was to get interested buyers educated, certified, and funded so that the down payment barrier was no longer a reason they couldn't buy. We kept hosting open houses. We kept promoting. But the condo sat. The Fire Sale With two weeks left on our contingency deadline, I knew we needed to do something drastic. We launched what I called a Fire Sale — and we told the whole story publicly. Not just "price reduced" and a Zillow listing. We got loud. We shared the situation, the timeline, the stakes. People responded to the honesty. The post got attention. Buyers who had been watching from the sidelines started paying attention. On the last possible day of our contingency window, we got an offer. The Win He sold his condo. He bought his dream property on California Trail. And somewhere on that land right now, his grandkids are running through the grass while eagles fish the slough. This is why I love this job. It's not always a straight line. Sometimes it's flooding and fire sales and homebuyer certification classes and open houses that feel like they're going nowhere. But when you stay creative, stay committed, and keep believing in the right outcome for your client — it comes together. Thinking About Making a Move in Whatcom County? Whether you're trying to sell in a tough market, navigating a contingency situation, or you're a first-time buyer who needs help understanding your options — I'd love to talk. I specialize in finding creative solutions for clients who have complex situations, and I'm one of the few agents in Whatcom County certified to teach the First Time Homebuyer Class so buyers can access free down payment assistance. Reach out anytime. Let's figure out what's possible. Andi Dyer | REMAX | Whatcom County Real Estate andi (at) andidyer.com
By Andi Dyer • June 18, 2026
The body content of your post goes here. To edit this text, click on it and delete this default text and start typing your own or paste your own from a different source.
By Andi Dyer • June 6, 2026
Receiving multiple offers is the scenario most sellers hope for — and it's more stressful than many expect. When you have two, three, or more offers in front of you, the decision feels high-stakes in both directions. Accept the wrong one and you may regret it. Overthink it and you may lose the best buyer you had. The sellers who navigate multiple offer situations most confidently are the ones who evaluate offers against a clear framework rather than a gut feeling — and who understand that the highest price isn't always the strongest offer. What's Really Going On in a Multiple Offer Situation Multiple offers typically arrive in one of two ways. Either the home generated enough early interest that several buyers submitted independently within a similar timeframe, or the seller — often with their agent's guidance — set a deadline and invited all interested parties to submit their best offer by a specific date and time. Both situations are genuine multiple offer scenarios, but they feel different. Organic multiple offers often arrive with varying terms and timelines, requiring the seller to evaluate offers that weren't designed to compete directly with each other. Deadline-driven multiple offers are more structured — buyers know they're competing and typically submit stronger terms than they would in a one-on-one negotiation. In either case, the seller's job is the same: evaluate what's actually on the table, understand the tradeoffs between offers, and make a decision they can feel confident in — not just on price, but on the full picture of each offer. What This Looks Like in Bellingham and Whatcom County In the current Bellingham market, multiple offer situations are most common for well-priced, well-prepared homes in active price ranges — particularly move-in ready homes in the $650,000–$800,000 range and accurately priced homes in neighborhoods with consistent buyer demand like Barkley, Fairhaven, and established areas near amenities. In smaller Whatcom County communities, multiple offers are less frequent but not unusual for homes that are genuinely well-positioned. When they do occur in markets like Lynden or Ferndale, the offers are sometimes fewer in number but can be equally competitive in terms. Understanding the local context — how common multiple offers are in your specific price range and neighborhood right now — helps calibrate expectations and strategy before offers arrive. The Framework for Evaluating Offers Price is the most visible component of any offer, but it's not the only one that matters — and in some cases it's not even the most important one. Net proceeds matter more than gross price. An offer at $720,000 with the buyer requesting $10,000 in closing cost assistance produces the same net as an offer at $710,000 with no concessions. Evaluating offers on a net basis rather than a headline price basis gives you a clearer picture of what each offer is actually worth. Financing strength is a critical variable. A buyer with a large down payment and a fully underwritten pre-approval is a meaningfully lower risk than one with a minimum down payment and a standard pre-qualification letter. Cash offers carry the least financing risk of all. In a multiple offer situation, financing strength is often what separates offers that look similar on price. Contingencies affect certainty. An offer with an inspection contingency, a financing contingency, and an appraisal contingency gives the buyer multiple exit ramps. An offer that waives the appraisal contingency — meaning the buyer will cover any gap between the appraised value and the purchase price — removes one of the most common sources of post-contract complications. Understanding what each offer's contingency structure means for the transaction's likelihood of closing successfully is part of a complete evaluation. Closing timeline matters for sellers who have specific needs on their end. A buyer who can close in twenty-one days may be more or less valuable to you than one offering forty-five days, depending on your situation. Sellers who need time to find their next home often find more value in a longer closing or a rent-back offer than in a marginally higher price with a compressed timeline. When the Decision Is Genuinely Difficult Sometimes two offers are close enough in every meaningful dimension that there's no obvious right answer. In those cases, it's reasonable to go back to the top one or two buyers and ask for their highest and best — giving them one opportunity to improve their offer knowing they're in competition. This should be done carefully and consistently — the same communication to each buyer, with the same deadline. Handled well, it can improve the terms of the best offer. Handled poorly, it can feel like a shakedown to buyers who submitted strong offers in good faith, and it occasionally causes the best buyer to withdraw. It's also worth remembering that no evaluation framework eliminates uncertainty entirely. Real estate transactions involve people, and people's circumstances change. The strongest offer on paper can still fall apart if the buyer's financing changes, their inspection concerns are serious, or their life situation shifts mid-transaction. The goal of thorough offer evaluation is to reduce that risk — not to eliminate it. What I Advise Clients When multiple offers arrive, I create a side-by-side comparison that shows each offer's key terms in a consistent format — net price after concessions, down payment and financing type, contingencies, proposed closing date, and any other terms that affect the seller's situation. That comparison takes the emotion out of the evaluation and makes the tradeoffs visible. Sellers who can see the offers laid out clearly alongside each other almost always reach a confident decision faster than those who are trying to hold multiple offer documents in their heads simultaneously. I also help sellers think through their specific priorities before the offers arrive if possible. What matters most to you — the highest net, the most certain close, the most flexible timeline? Knowing your priorities in advance makes the evaluation faster and the decision cleaner. Why Planning and Timing Matter Multiple offer situations reward sellers who have done their pricing and preparation work thoroughly. A home that is accurately priced and well-presented is more likely to generate the kind of early, concentrated interest that produces multiple offers. And a seller who understands their market clearly is better positioned to evaluate those offers confidently — knowing whether the offers on the table are genuinely strong or merely the best of a weak field. The preparation that produced the multiple offer situation is also what gives the seller the confidence to evaluate and decide without second-guessing. A seller who knows their home is well-priced and well-prepared approaches the decision from a position of strength rather than anxiety. The Bottom Line Evaluating multiple offers without regret requires looking beyond the headline price to the full picture of each offer — net proceeds, financing strength, contingency structure, and closing timeline. The highest price isn't always the strongest offer, and the strongest offer isn't always the most obvious one. Sellers who approach this moment with a clear framework and a good understanding of their own priorities consistently make decisions they feel confident in — not because the outcome is guaranteed, but because the decision was made thoughtfully. If you're trying to balance patience with smart action, start here: 👉 Start with a low-pressure home value and seller planning tool: https://www.andidyerrealestate.com/seller/valuation/ About the Author Andi Dyer is a Bellingham-based real estate broker with REMAX Whatcom County, specializing in helping longtime homeowners and sellers make confident, well-informed decisions. With a calm, data-driven approach and strong negotiation expertise, Andi focuses on protecting equity, reducing stress, and guiding sellers through the process with clarity and care. 📍 Serving Bellingham and all of Whatcom County 📞 Call or text: 360 • 734 • 6479 📧 Email: andi [at] andidyer [dot] com Zillow · Realtor.com · Homes.com · Google Business · Facebook · Instagram
By Andi Dyer • May 24, 2026
Every so often I work with a seller whose situation does not fit neatly into the usual real estate conversation. This was one of those. The home had been in the family for years. His in-laws had built their life there — raised children, hosted holidays, made memories that mattered. But they were gone now, and the house sat empty, quietly accumulating costs. Taxes. Utilities. Maintenance that kept getting pushed back. A roof that was not going to wait forever. What had once felt like a gift had slowly become something else: a financial obligation with no clear end date. He was not in crisis. He was not in a rush. He simply wanted someone to sit down with him, look at the real numbers, and tell him honestly what his options were. That is what we did. 
By Andi Dyer • May 15, 2026
The body content of your post goes here. To edit this text, click on it and delete this default text and start typing your own or paste your own from a different source.
By Andi Dyer • May 13, 2026
For longtime homeowners in Bellingham and Whatcom County — particularly those who bought their home in the 1990s or early 2000s — the single most significant financial question at the point of sale is usually some version of "how much of this is taxable?" Equity accumulated over twenty or thirty years in a Pacific Northwest market that has seen sustained appreciation can easily be several hundred thousand dollars, sometimes substantially more. That gain is not automatically tax-free, but most of it, for most homeowners, is. Understanding how that works — clearly, without the jargon, and with the specifics that actually matter — is one of the most valuable things a seller can do well before listing. The short version is that the federal tax code allows a homeowner to exclude up to $250,000 of capital gain from the sale of a primary residence if filing as a single taxpayer, or up to $500,000 if married filing jointly. Gains above those amounts are taxed as long-term capital gains at the applicable federal rate, with no Washington State income tax to add to the federal bill. The exclusion applies if the homeowner has owned and used the home as their primary residence for at least two of the last five years before the sale. That's the core rule. The nuance, and the places where longtime homeowners sometimes run into surprise, is in the edges of that rule rather than the center. What "capital gain" actually means for a home Capital gain, in the context of a home sale, is not the full sale price. It's the difference between what you sell the home for — net of selling costs — and what you paid for it, adjusted for certain improvements you've made over the years. The formal term for your adjusted purchase price is your "basis" or "cost basis." If you bought your home in 1998 for $180,000, added a $40,000 addition in 2006, and sell it in 2026 for $750,000 with $45,000 in selling costs, your gain is not $570,000. It's roughly $485,000 — the sale price minus the selling costs minus the original purchase price minus the improvement. This matters because $485,000 of gain for a married couple is fully within the $500,000 exclusion. Zero federal capital gains tax owed. For a single homeowner in the same situation, $485,000 of gain is $235,000 above the $250,000 exclusion, taxed at long-term capital gains rates — meaningful, but still dramatically less than the gross numbers would suggest. Getting the basis right is therefore one of the most underappreciated parts of preparing for a sale. Every significant improvement made over the years — additions, new roof, kitchen remodel, new windows, hardscaping, HVAC replacement — can add to basis if it's a true improvement rather than a repair. Repainting a wall doesn't add to basis. Replacing the whole roof does. For homeowners who have been in a home for a long time, reconstructing this history before sale can shift the tax picture by tens of thousands of dollars. The ownership and use tests The exclusion applies if you've owned and used the home as your primary residence for at least two years out of the last five years before sale. The two years don't have to be consecutive, and they don't have to be the most recent two. This matters for a few specific situations. A homeowner who moved out of their home and rented it for a year before selling can still claim the full exclusion, as long as they meet the two-out-of-five rule. A homeowner who owns two homes and is deciding which to sell may have flexibility around which qualifies as "primary" based on the facts of how the homes were used. A homeowner who converted a home from rental to primary residence (or vice versa) has a more complicated calculation that depends on the percentages of time in each use. For most Bellingham homeowners selling their long-term primary residence, the test is straightforwardly met and isn't something to worry about. But for homeowners with more complex property histories, the details matter and deserve specific attention. The frequency limitation A homeowner can only claim the full exclusion once every two years. This rarely affects retirees and longtime homeowners — most are selling a home they've been in for decades. But for sellers who have recently used the exclusion on a prior home (within the last twenty-four months), the exclusion may not be available for the current sale. Gains above the exclusion For longtime Bellingham homeowners with substantial equity, it's increasingly common for the taxable gain after the exclusion to be non-trivial. A married couple selling a home purchased thirty years ago with a current gain of $700,000 has $200,000 of gain above the exclusion, taxed at long-term capital gains rates. At the federal long-term capital gains rate applicable to many retirees (15% for the typical tier, 20% for the highest), that's $30,000–$40,000 of federal tax. Significant, but a much smaller bite than the same gain would produce if all of it were taxable. For single filers, or widowed spouses who have lost the joint filing eligibility, the math tightens quickly. A widowed spouse who sells within two years of the spouse's death can still use the $500,000 exclusion under a specific provision of the tax code. After that two-year window, only the $250,000 single-filer exclusion is available. This is one of the situations where timing, within a planning horizon, can make a meaningful financial difference. What increases and doesn't increase basis Improvements — substantial work that adds value, prolongs useful life, or adapts the property to new uses — add to basis. A new roof, a new furnace, an addition, a finished basement, a new deck, a new driveway, new windows, major plumbing replumbing, electrical panel upgrades, kitchen and bathroom remodels — all add to basis. Repairs and routine maintenance do not. Fixing a leaky faucet, repainting the exterior, replacing a few broken shingles, routine furnace service — these don't add to basis, even though they keep the home in good condition. The distinction between "improvement" and "repair" is sometimes fuzzy, and the IRS has guidance on it. Work that restores the home to its prior condition is usually a repair. Work that upgrades the home to a better condition is usually an improvement. Selling costs — the real estate commission, title and escrow fees, recording fees, and certain other closing costs — are subtracted from the sale price when calculating the gain, effectively reducing the taxable amount. This is why net proceeds matter more than gross sale price for tax purposes. Records matter more than people expect The single most common regret among longtime homeowners at the point of sale is not having records of improvements made over the years. Receipts from a 2004 kitchen remodel, invoices from a 2011 roof replacement, contractor records from a 2015 addition — these matter directly to the gain calculation, and reconstructing them after the fact can be time-consuming or impossible. If a sale is within a one to three year horizon, beginning to gather these records is one of the quieter but most valuable preparation tasks. Even approximate records supported by dated photos, canceled checks, or contractor names can help substantiate improvements on a tax return. The IRS generally accepts reasonable substantiation; it does not require perfection. Washington State specifics Washington does not have a state income tax, which means there is no state capital gains tax on the sale of a primary residence for the overwhelming majority of sellers. (Washington does have a capital gains tax on long-term gains from certain financial assets above a threshold, but that tax specifically excludes real estate sales.) Washington does have a real estate excise tax (REET) paid at the time of sale, which is effectively a transfer tax rather than an income tax. REET is paid out of the sale proceeds at closing and is separate from capital gains. For most Bellingham sellers, the tax analysis is therefore a federal-only analysis, which simplifies things considerably compared to states with income taxes stacked on top. What this actually means for planning For most longtime Bellingham homeowners selling a primary residence, the combination of the $250,000 / $500,000 exclusion, proper basis documentation, and the absence of state income tax means that the majority of the gain is likely to be tax-free, and the portion that is taxable is taxed at long-term capital gains rates rather than ordinary income rates. That's often a more favorable picture than sellers initially expect. The places where this can go sideways are: insufficient basis documentation that leaves money on the table; widowhood situations where the two-year window for the $500,000 exclusion has closed; rental-to-primary conversions that complicate the calculation; and sales within two years of a previous primary residence sale where the exclusion isn't available. Each of these deserves a specific conversation with a CPA or tax advisor in advance of listing. A quieter way to think about this The tax picture of a home sale is rarely as punishing as longtime homeowners fear. For a very large portion of Bellingham sellers, the exclusion covers the entire gain, and the sale is federally tax-free. For sellers with gains above the exclusion, the tax is real but manageable and usually represents a small percentage of the total equity being realized. The work worth doing in advance is gathering records, confirming the basis, and having a brief conversation with a tax professional to verify the specifics for your situation. That work produces a clear number rather than a vague worry, and a clear number is almost always easier to plan around. Frequently asked questions Do I owe capital gains tax if I reinvest the money into another home? Not because of the reinvestment itself. The old "rollover" rule that required buying another home to defer tax was replaced by the current exclusion system in 1997. The exclusion applies whether or not you buy another home. What about a 1031 exchange? A 1031 exchange applies only to investment property, not to a primary residence. For a home you've lived in as your primary residence, the exclusion is the applicable rule, not a 1031 exchange. Do I need to report the sale if the entire gain is excluded? Generally not, if you receive Form 1099-S from the closing agent and the entire gain qualifies for exclusion. If the gain exceeds the exclusion or if you don't meet the ownership and use tests, the sale must be reported. Your CPA can confirm which applies. How are selling costs handled? Commissions, closing costs paid by the seller, and certain other costs reduce the sale price for purposes of calculating the gain. They are not separately deductible; they're netted into the gain calculation. Related reading  *What Longtime Homeowners Often Get Wrong About Their Home's 'Basis'* goes deeper into basis calculation, and *How Long-Term Equity Changes the Math on Whether to Sell or Hold* addresses how the equity picture affects broader planning decisions.
More Posts