The 16 Best Places to Live in the U.S.: 2016

Andi • August 18, 2016

We talked to climbers, Olympic mountain bikers, musicians, and award-winning chefs about what exactly makes their hometowns so special and fun

It’s easy to fantasize about living in one of these 16 adventure meccas, but to really understand how great they are, you have to be on the ground.

Billings, Montana

Population: 110,000

Billings
  Photo: Peter Frank Edwards

When it comes to fitting you for a cowboy hat, the gals at Taubert’s Ranch Outfitters have two ways to go about it. If the hat is a little tight, they’ll point out, your head will stretch it over time. If it’s loose, they’ll advise you to stuff the band with some newspaper. Nothing fancy, problem solved.

Taubert’s, purveyor of hats, cowboy boots, and Pendleton blankets, has been on North Broadway in downtown Billings since 1979. Back then this shopping district was a cen-ter of commerce for ranchers who traveled from hundreds of miles away. In the decades since, Billings’s population has grown from about 67,000 to more than 110,000. But Lou Clayton, 82, who’s been clocking in at Taubert’s since 1989, says Billings is a small town dressed up like a big city. “We used to say, ‘You can tell when you get to Montana, because people wave at you on the two-lane roads,’ and that’s still true today.”

Billings is only a stone’s throw from the Absaroka-Beartooth Wilderness area, one of the largest in the country and home to Granite Peak, Montana’s tallest at 12,807 feet. Anglers enjoy the wide, ­braided waters of the Bighorn River to the east and the boulder-strewn Stillwater ­River to the west. The hills to the northwest are a playground for climbers, trail runners, and mountain bikers, and Yellowstone National Park is less than three hours away. Better yet, it’s all substantially more affordable than already discovered Montana adventure hubs like Missoula and Bozeman—the median house price in Billings is still under $200,000.

As an energy and agricultural center known for both its stunning rimrock formations and its oil refineries, Billings was a dark horse in this year’s competition. Locals were pleasantly surprised to see their scrappy city defeat scenic Jackson, Wyoming, in the final round.

Jackson, Wyoming

Population: 10,523

Grand Teton National Park
  Photo: Jimmy Chin

It’s never been easy to live in Jackson. It’s remote, the winters are long and bitterly cold, and the soil is bad for farming and ranching. It’s also very expensive: the average home price in 2015 was over $1 million. For all the challenges, though, Jackson is a hard place to leave.

“I’m a classic example of that,” says Nat Patridge, 45, co-owner of Exum Mountain Guides, a local institution. “I moved out here 23 years ago for the winter and then never considered leaving.” Jackson’s attractions are legendary: it’s the gateway to two of the national park system’s crown jewels, Yellowstone and Grand Teton, and it offers some of the best skiing, hiking, mountaineering, wildlife watching, fishing, hunting, and whitewater you’ll find anywhere.

The Tetons rise 7,000 feet straight up from the valley floor, begging to be climbed, and the mountaineering history here is as long and rich as anywhere in North Amer­ica. But Jackson is equally ­famous for skiing—two decades ago, Patridge’s first job in town was working on Jackson Hole Mountain Resort’s red tram.

The fun isn’t confined to the peaks. People come here from everywhere to fish for trout on the Snake River, hunt elk from the famous National Elk Refuge herd, or just gaze at wildlife through binoculars. “On my commute to the park, it’s rare I don’t see some kind of megafauna—elk, bison, moose, wolf,” Patridge says.

The three million tourists who flow through town every summer raise stress levels for local citizens, but they bring in plenty of revenue for businesses, too. As do the superrich part-time residents whose mansions bigfoot the scarce land available for housing. More than 1,500 deed-restricted “affordable and attainable” homes have been built in the past 25 years, but many thousands of workers face difficult commutes over Teton Pass from places like Victor, Idaho, or more than an hour down Snake River Canyon in Alpine, Wyoming.

In the face of those challenges, Patridge says that people who stay “are extraordinary—resilient and driven and self-motivated.” Talent and prosperity have given rise to one other success ­story: a thriving local arts scene. “My kids can participate in Jackson’s ski programs and then, on the same day, excellent dance, pottery, and arts programs,” says Patridge. “There aren’t many places where they have those oppor­tunities.” ­ —­Frederick Reimers

Denver, Colorado

Population: 682,545

best-towns-16-denver.jpg
  Photo: Courtesy of Lula Rose

Colorado’s capital is one of the fastest-growing places in the country—transplants are drawn to big-city living within striking distance of 14,000-foot peaks and Rocky Mountain skiing and biking. “I was born in Denver, but I get it,” says Neyla Pekarek, 29, who plays cello with the Lumineers. “The weather is awesome, the people are friendly, and there’s nothing pretentious about it. I’ve seen a lot of places, but I still want to live here.” —Anna Callaghan

Yachats, Oregon

Population: 718

2016
  Photo: Isaac Lane Koval

First, you should know that it’s “yah-hahts,” not “yah-chats” or “yach-ettes.” It’s also Oregon’s loveliest sea­side town. Only about 700 salt-crusted souls live here, along one of the most stunning stretches of Pacific Northwest coastline—think lighthouses and peaks of the spruce-covered Coast Range close to a deep-blue sea. Charlie Van Meter, 28, moved here with his wife, Jenna, in May 2015 to become the first brewmaster at newly opened Yachats Brewing. When it’s quitting time, they fat-bike along the beach, hike to a stone hut with airy ocean views along Cape Perpetua, or wander through the rich coastal rainforests looking for chanterelles. Afterward, Van Meter recommends stopping by the brewery for the house-smoked salmon chowder paired with a pint of his 10 Mile saison. “Yachats is a great place to raise a dog, too,” he says. “At low tide, everyone heads down to the beach to let them stomp around. —Tim Neville

Taos, New Mexico

Population: 5,740

Taos
  Photo: Sam Lambie

“It’s all about the landscape here,” says Brooks Thostenson, 29, cofounder of Taos Mountain Energy Bars, which makes its delicious products in the area. “It’s unique: right where the high desert meets the Rockies.” This favored location means year-round outdoor fun. When it’s cold, the action is on the steep, bone-dry powder at Taos Ski Valley. Come summer, there’s Class IV boating on the Rio Grande, soaking at Black Rock Hot Springs, and mountain biking on the famed alpine singletrack of the South Boundary Trail. The unbeatable scenery and manageable cost of living don’t just draw the Gore-Tex set: hippies living in off-the-grid “earthship” houses, artists like pioneering minimalist Agnes Martin, and A-listers like Julia Roberts have been enchanted, too. The place feels older than most boom-town ski destinations for good reason: Taos Pueblo, north of town, has been inhabited for more than a thousand years. “There’s just an amazing melding of cultures and a really laid-back vibe here, ” Thostenson says. —Anna Callaghan

Steamboat Springs, Colorado

Population: 12,260

Colorado
  Photo: Noah Wetzel

It could be Steamboat’s distance from Denver—three hours when there’s no snow on the roads—or its roots as a rough-and-tumble ranching community, but this place has a noticeably more laid-back feel than most world-class resort towns. Bill Gamber, 52, cofounder of camping-gear maker Big Agnes and sports-nutrition company Honey Stinger, says it’s all about the terrain. Steamboat’s ski hill is a bit mellower compared with places like Jackson Hole and Telluride, and the timber-covered slopes “attract a less extreme and therefore more relaxed population,” says Gamber.

That doesn’t mean the alpha athletes aren’t here—Steamboat has sent 88 competitors to the Olympics. Kids can take the Wednesday-night ski-jumping clinics at the tiny Howelsen Hill ski area; Gamber is partial to hitting the 12 miles of World Cup nordic-ski trails or skinning up Steamboat ski resort (2,965 acres and 3,668 vertical feet) before work. During the summer, you’ll find him mountain-biking the growing network of singletrack. In 2013, voters approved spending $5.1 million of hotel-tax revenues to add 130 miles to Steamboat’s system of bike trails. Other amenities include Fish Creek, a Class V test piece inside city limits, and a pair of rowdy kayak waves on the Yampa River. Gamber is an asset himself—the jobs he provides keep about 100 peo­ple busy, as do companies like Kent Eriksen Cycles, Moots, and Smartwool, whose employees can ski, fish, paddle, or ride on their lunch break. Apparently, recruitment isn’t difficult. —­Frederick Reimers

Ludington, Michigan

Population: 8,058

best-towns-16-ludington.jpg
  Photo: John McCormick

It all starts with the water. Ludington State Park (5,300 acres) and the adjoining Nordhouse Dunes Wilderness Area (3,450) have a combined ten miles of Lake Michigan frontage. What’s more, Hamlin Lake, which forms the eastern boundary of the state park, is warm, and its outflow into the big lake heats up the usually frigid waters early in the season. “So instead of it being 60 degrees, you have 70-degree water,” says 20-year resident Andy Klevorn, the head of technology for the school district and a cyclist and paddler when he’s off the clock. Then there’s the 64-mile Pere Marquette River, a blue-ribbon fishery that flows through 540,344-acre Manistee National Forest before reaching the Great Lakes.

But Ludingtonites like Klevorn aren’t content to just live in a waterfront town. They’ve been building out singletrack, too. “When we finish the system on the north side of town, we’ll have 12 to 13 miles of groomed trails in the city limits,” says Klevorn. When that’s not enough, he and other members of the Shoreline Cycling Club ride events like the Lumberjack 100 mountain-bike race—or hop on fat bikes to tackle the area’s frozen lakes. “There’s 35 miles of world-class singletrack within a half-hour’s drive,” Klevorn says. “I’ve ridden in Italy, Colorado, and North Carolina, and this is as good as any of them.” —­Jonah Ogles

Boise, Idaho

Population: 218,281

best-towns-16-boise.jpg
  Photo: Chad Chase/Idaho Stock Images

Mat Erpelding, 41, represents Boise’s Downtown and North End in the Idaho state legislature, which means his district contains the majority of the city’s famous 190-mile Ridge to Rivers system. “The trails are the reason I live in Boise,” says Erpelding, owner of Idaho Mountain Guides, which leads rock-climbing trips in the area. Above, he walks us through his ideal Boise day: a bike-based quadrathlon via the Greenbelt, a 25-mile path along the Boise River. —­Frederick Reimers

Bellingham, Washington ***

Population: 85,146

25-29 Years
  Photo: Christopher Kimmel

This coastal college town’s nickname is the City of Subdued Excitement, and if that sounds a little low-key to you, no less an authority than American Alpine Institute president Dunham Gooding says you’re taking it all wrong. “It means we’re psyched but civilized,” the 41-year Bellingham resident says. “I guide in six states and 16 countries, and you couldn’t design a better place to be based.” Situated on Bellingham Bay, the town is a ferry away from prime sea kayaking and whale-watching in the San Juan Islands. A 90-minute drive to the east are the rugged, glaciated peaks of North Cascades National Park. The closest ski area, Mount Baker, is known for its relaxed vibes and staggering snowfall—a ten-year average of 654 inches, more than double Aspen’s. “People of all ages are outside a lot of the time. It’s too beautiful not to be,” Gooding says. “It’s a city of doers.” —Anna Callaghan

Hanalei, Hawaii

Population: 450

best-towns-16-hanalei.jpg
  Photo: Tyler Stableford/Gallery Stock

Before Dave McEntee makes 200 pounds of tasty taro burgers for his wholesale operation, Braddah Dave’s, he heads out for a two-hour dawn patrol on Hanalei Bay. “Actually, I try to get in two surfing sessions every day—one before work and one after,” says the 46-year-old entrepreneur, who moved to the island of Kauai from the mainland 18 years ago to start a farm. The town of 450 people doesn’t offer much—a grocery store, some cafés and restaurants, and board shops—but surfing is what life here is all about, ­especially in winter, when heavy hitters like Laird Hamilton tow into the monster swells that jack up in the reliable off-shore breeze.

Newcomers shouldn’t worry, though. “You can have 40-foot waves outside, but they’ll only be two feet by the pier,” McEntee says, adding that dozens of breaks along the two-mile-long white-sand bay offer lefts, rights, tubes, mush, or whatever you want. On flat days, McEntee rides horses into the jungle or cruises a stand-up paddleboard along the Hanalei River. The 6,175-acre Na Pali Coast State Wilderness Park, including its spectacular 11-mile hike to a secluded beach, sits just a few miles west.

Living in a vacation hot spot means high prices and limited employment prospects. But to hear McEntee tell it, it’s all worth it. “This place keeps me on my game,” he says. “I can’t tell you how great it is to be out surfing the best waves and then turn around to see waterfalls lighting up the background. It all feels so healthy. — Tim Neville

Gunnison, Colorado

Population: 6,076

Bike
  Photo: Petar Dopchev Photography

Gunnison is one of those favored Colorado hamlets whose elevation (7,700 feet) is higher than its population, and it’s a joy to be here year-round. “I came for skiing at Crested Butte”—the resort is up the road—“but stayed for the Gunnison summers,” says Carollyn Cherry, 53, manager of Scenic River Tours and a 28-year resident. Nearby Gunnison National Forest and Black Canyon of the Gunnison National Park make it easy to play. Beyond that, “It’s just a very active, socially conscious, friendly place.” — Anna Callaghan

Bend, Oregon

Population: 87,014

cascades
  Photo: Bruce McCammon Photography

Woody Woodward wanted three things out of life, and he found them all in this city on the sunny, dry side of the Cascades, three and a half hours southeast of Portland. “My goals were to be on a beer label, have a ski trail named in my honor, and a mountain-bike trail, too,” says the city’s former mayor, who came to Bend in 1978. Mission accomplished. Woodward has a pair of namesake trails, and his likeness graced bottles of Silver Moon’s Epic Trail Ale, a local brew.

Bend has grown from 14,000 residents to nearly 90,000 since Woodward arrived, and much else has changed, including housing costs. (The median home price has risen over $300,000.) The city now has at least 16 breweries, a whitewater park, and a $11.4 million rec center featuring a combination ice rink and pickleball arena. For this coming winter, Mount Bachelor, 22 miles southwest of town, is installing a high-speed quad to access 635 acres of new ski and snowboard slopes, an expansion that will make the volcano the fifth-largest ski area in the U.S. In the summer months, Phil’s Complex, an approximately 300-mile network of singletrack, is just a 20-­minute pedal from downtown. These riches have drawn more than 70 outdoor-product companies to Bend, including Cairn, Hydro Flask, and Ruffwear. Not bad for a once broke timber burg.

For Woodward, the best part of Bend is how what’s on offer always seems to match his ambitions. That 50-mile trail run around the icy Three Sisters peaks? It’s an excellent goal when you have time to train, as is the 12-mile loop among the asters up Soda Creek to Green Lakes and back. Maybe you’ll finally flash a 5.11 out at Smith Rock, 40 minutes away, or take a paddleboard out on the Cascade Lakes. But your adventures here don’t have to be that hardcore—the mile-long walk up Bend’s in-town volcano, Pilot Butte, is ideal for sunset hikes. “Bend is accessible to so many people in that way,” Woodward says. “Sharing the experience is what’s really ­important—not just getting your ass kicked.” Oh, and
for the record: Wood­ward is 76. Of course, in Bend years that’s more like 55. — Tim Neville

Ketchum, Idaho

Population: 2,728

  Photo: Alice Scully/iStock

Sun Valley, right next door to Ketchum, was America’s first ski resort and the site of the world’s first ski lift, developed in 1936 from a conveyor used to move bananas off ships. Skiing is still central to the community’s spirit. The mountain helped start the ski-racing careers of brothers Zach and Reggie Crist, both U.S. Ski Team members and X Games ski-cross medalists. The irony, says Zach Crist, is that the better skiing (and climbing and hiking) can be found in any of the four other, wilder mountain ranges surrounding Ketchum—the Pioneers, the Boulders, the White Clouds, and the Sawtooths.

“The Pioneer Mountains to the east are as close to the Alps as you get in America,” says Crist, “and the Sawtooths contain some of the best couloir skiing in the world, but you better have your shit together.” (Saw-tooth Mountain Guides, where Crist works, can help you with that.) With its ritzy history and fine-dining and drinking establishments (we like the Pioneer Saloon to get a little fancy and Grumpy’s for something more casual), plus hundreds of miles of manicured ski slopes and singletrack, Ketchum has a glamorous face. But, as Crist says, “Venture a few miles off-road and you’re in some of the wildest country in the lower 48.” —­Frederick Reimers

Grand Marais, Minnesota

Population: 1,327

Ackerman + Gruber
  Photo: Ackerman + Gruber

This one-stoplight town, nestled between Superior ­National Forest and Lake Superior, is the only municipality in Cook County, which is nearly three times the size of Rhode Island. That makes it the de facto gateway to the 1.1-million-acre Boundary Waters Canoe Area Wilderness to the north. This attracts an action-ready crowd: “Canoeing, kayaking, biking, hiking, sailing, fishing, skiing, snowshoeing, dogsledding, and rock climbing are just some of the outdoor activities that draw people,” says Dave Freeman, a local who’s been here 15 years and, in 2014, was named a National Geographic Adventurer of the Year, alongside his wife, Amy, for completing an 11,700-mile kayak and ­dogsled traverse of North Amer­ica. “It’s a small, welcoming community with vibrant arts and music scenes, a host of great restaurants, microbrew­eries, and art galleries. It’s also a great place to relax and skip stones, enjoy a cool breeze off the lake, read a book, or just be.” — Anna Callaghan

Durango, Colorado

Population: 18,006

best-towns-16-durango.jpg
  Photo: Michael Deleon

“People don’t move here for a job,” says Todd Wells, 40, a three-time Olympic mountain biker and a resident for 22 years. “They move because they love mountain biking or kayaking or another out­door activity, and then they figure out a way to make it work.” It’s easier to pull that off here than in most Colorado mountain towns. The median home cost is $360,000—pricey, but affordable compared with most first-class Rocky Mountain meccas. And Durango is certainly first-class; residents get after it all year long. We asked Wells how to make the most of each season.

Fall : “The Colorado mountains are spectacular in autumn,” says Wells, and the San Juans north of Durango are home to one of the highest concentrations of fourteeners in the state. Hike through yellowing aspens on a 2.4-mile trail on the flank of Engineer Mountain, 35 miles north of town.

Winter : The 1,360-acre Purgatory Ski Resort, 35 minutes from downtown, averages 260 inches of snow per year and is ideal for families, beginners, and people who don’t like lines. The tiny in-town ski area, Chapman Hill, stays open in the evenings, so kids (and parents) can shred after school.

Spring : “Most of the trails in town become rideable in the spring, so it’s a great time to mountain-bike,” says Wells. There are multiple trail systems, like Horse Gulch, that start right in town, and the International Mountain Bicycling Association’s Epic-­certified Colorado Trail starts just outside.

Summer : North of Durango, the Animas River is churning Class V whitewater. Closer to downtown it mellows out. “My favorite thing is to just tube it, floating from 32nd Street down to the Ninth Street Bridge,” says Wells. “On a summer day, it’s a big party down there!” —Anna Callaghan

Seattle, Washington

Population: 684,451

alone
  Photo: Michael Hanson

You’ll hear people from the eastern part of the state call Seattle “the coast.” And while that’s not strictly accurate, it doesn’t feel far off. From the top of the 605-foot Space Needle, you can watch sailboats drift on Lake Union and green and white ferries zigzag across Puget Sound. “To have a city situated in a place this beautiful, with mountains and water? That’s exceptional,” says Renee Erickson, 43, a Seattle native who owns five restaurants and a coffee shop in town. Three national parks and six ski resorts are within a three-hour drive, and they don’t call Seattle the Emerald City for nothing—green space is abundant, with some 465 city parks. The local job market is strong, thanks in part to giants like Amazon and Microsoft.

There are downsides, of course. Though home prices aren’t quite as bad as, say, San Francisco, the median is around $500,000, and houses in the most desirable neighborhoods command much more. And as you might have heard, it rains from time to time. But newcomers are undeterred, making Seattle one of the country’s most popular cities. “That energy is great,” says Erickson. “People come from all over the world to get the best of everything, from the outdoors to jobs.” —Anna Callaghan

Pack It In

Renee Erickson’s ideal Seattle day

7:30 A.M.
Grab coffee and an almond croissant at Coyle’s Bakeshop in Greenwood.

9:30 A.M.
Spend a few hours on the water at the Shilshole Bay ­Marina. Try your hand at salmon fishing or just enjoy the views.

12 P.M.
“The city’s focus on museums is incredible,” Erickson says. Head to the Seattle Art Museum to take in some downtown culture.

5:30 P.M.
Stop into Upper Bar Ferdinand for a glass of sparkling wine from an independent Pacific Northwest producer.

7 P.M.
Have dinner at Bar Melusine, ­Erickson’s airy seafood spot.

8:30 P.M.
Grab ice cream at Kurt Farm Shop, where milk, cream, and eggs are sourced from nearby Vashon Island, across the water.



By Andi Dyer • September 11, 2026
I recently had the opportunity to represent the buyer on this Blaine home, and it’s a good time to look at what’s happening in the 98230 market. August numbers show a market giving buyers a little more breathing room: • 184 homes for sale, up 17.2% from last year • 5.9 months of inventory, up from 5.2 months • Homes that sold took 73 days on market, compared with 32 days last August • The median sales price was $569,950, up 3.6% What does that mean for buyers? More choices, more time to evaluate a property, and potentially more room to negotiate, depending on the home. But it’s not a bargain-bin market. Blaine prices are holding relatively steady, so understanding the individual property, its competition, and the seller’s position still matters. 𝗠𝗼𝗿𝗲 𝗶𝗻𝘃𝗲𝗻𝘁𝗼𝗿𝘆 𝗰𝗿𝗲𝗮𝘁𝗲𝘀 𝗼𝗽𝗽𝗼𝗿𝘁𝘂𝗻𝗶𝘁𝘆. 𝗚𝗼𝗼𝗱 𝘀𝘁𝗿𝗮𝘁𝗲𝗴𝘆 𝗵𝗲𝗹𝗽𝘀 𝘆𝗼𝘂 𝘂𝘀𝗲 𝗶𝘁.
By Andi Dyer • August 28, 2026
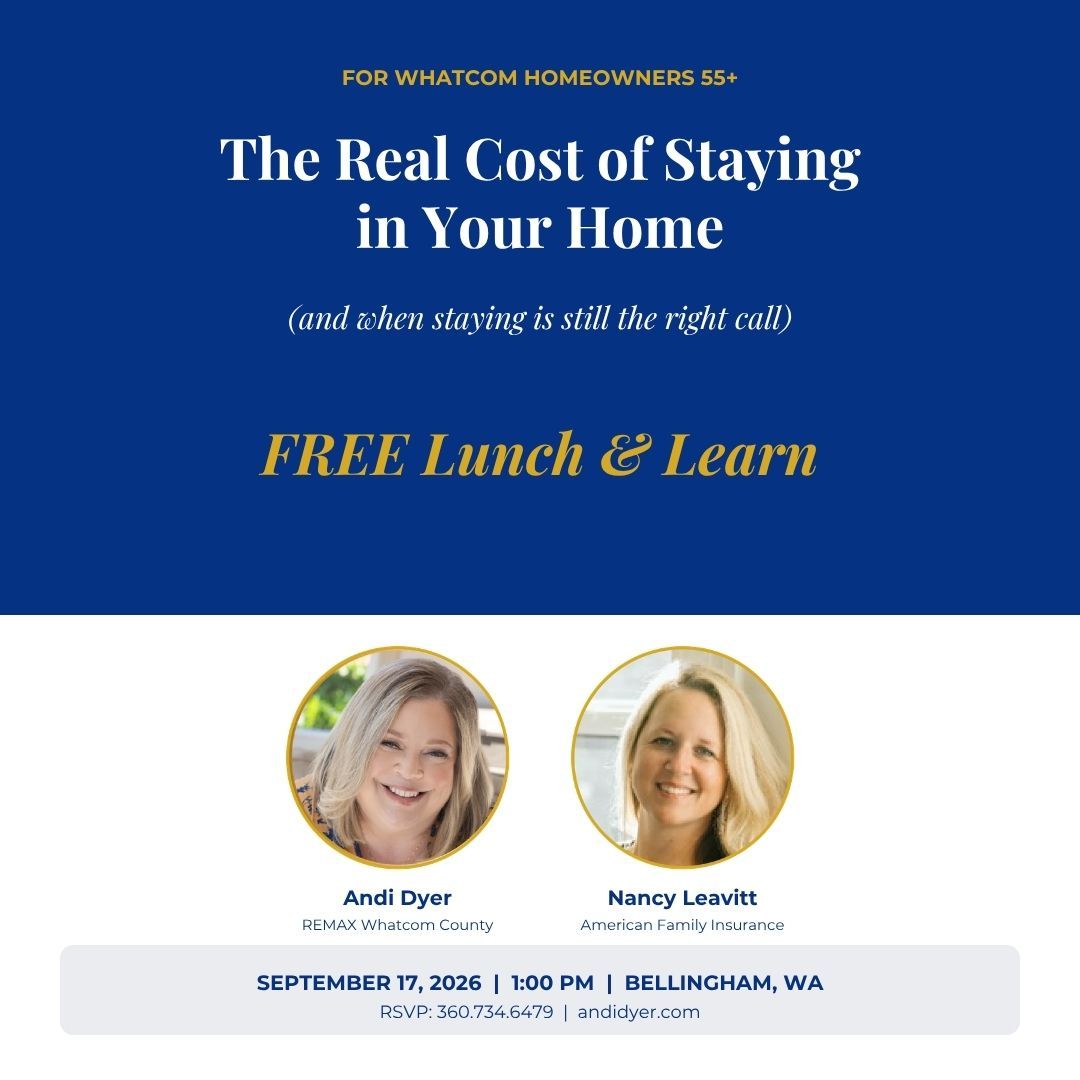
 Deciding whether to sell your home, downsize, or stay where you are comes down to more than your home's value. For Whatcom County homeowners, the right decision should consider your equity, monthly housing costs, maintenance, insurance, accessibility, lifestyle, and what it would actually cost to move. Sometimes selling and right-sizing makes sense. Sometimes staying in your current home is the better financial decision. The important thing is knowing the numbers before you decide. Should I Sell My Home or Stay? If you're wondering whether it's time to sell your home, start with one question: Does my home still fit the way I live today? A home that was perfect 10 or 20 years ago may now have unused bedrooms, stairs you don't enjoy, a large yard to maintain, or repairs you would rather not tackle. On the other hand, a home that's paid off or has a low mortgage payment can be difficult to replace affordably. That's why I encourage homeowners to look at the entire picture before assuming downsizing will save money. Is It Cheaper to Stay in Your Home or Downsize? Not necessarily. A smaller home can reduce utilities, maintenance and property upkeep, but moving comes with its own costs. A replacement home may have a higher price per square foot, HOA dues, increased property taxes or a new mortgage at today's interest rates. When comparing staying versus selling, consider: Mortgage payment and remaining loan balance Property taxes Homeowner's insurance Utilities Landscaping and property maintenance Upcoming repairs or renovations HOA dues at a potential replacement property Cost of buying or renting your next home Moving and selling expenses Your estimated proceeds and available equity after a sale The better question isn't simply, "Would a smaller house cost less?" It's "Which housing choice makes the most financial and practical sense for the next stage of my life?" What Does Right-Sizing Your Home Mean? Right-sizing means choosing a home that fits your current lifestyle, rather than simply moving into a smaller house. For some homeowners, that means fewer bedrooms and less yard work. For others, it might mean one-level living, a primary bedroom on the main floor, fewer stairs, better accessibility, or living closer to family, medical care, shopping and friends. And sometimes right-sizing means staying exactly where you are and making your current home easier to live in. Is Aging in Place a Better Option? For many Bellingham and Whatcom County homeowners, aging in place can be an excellent option if the home can safely and affordably meet their long-term needs. Consider whether your current home has: A bedroom and full bathroom on the main level Manageable stairs and entryways A reasonable amount of property to maintain Access to transportation, shopping and healthcare Space that could be modified for future accessibility Maintenance and repair costs that fit comfortably within your budget You may find that a few thoughtful improvements make staying in your home far more practical than moving. How Much Is My Whatcom County Home Worth? Knowing your home's current market value is one of the most important pieces of the stay-or-sell decision. Your estimated equity can help determine what choices are realistically available to you. Online home-value estimates are a useful starting point, but they may not accurately account for your home's condition, renovations, neighborhood, view, acreage, outbuildings or other features that affect buyer demand. A local real estate market analysis can provide a more detailed estimate based on recent comparable sales and current competition in the Bellingham and Whatcom County real estate market . And getting that information doesn't mean you've decided to sell. Sometimes knowing what your home is worth gives you the information you need to confidently decide not to sell. What Should I Consider Before Downsizing? Before putting your home on the market, ask yourself these questions: 1. What would I realistically net from selling my home? Your home's sale price and the amount you walk away with are two different numbers. Consider your mortgage balance, selling expenses and other potential costs. 2. What will my next home cost? Look at actual homes that meet your needs rather than assuming smaller automatically means cheaper. 3. Will moving improve my daily life? Consider maintenance, stairs, location, accessibility, transportation and proximity to the people and activities important to you. 4. Are major home expenses coming? A roof, siding, heating system, septic system or other major project can change the financial comparison. 5. Could I modify my current home instead? Sometimes remodeling a bathroom, improving accessibility or hiring help with landscaping costs considerably less than moving. Should I Review My Homeowner's Insurance Before Deciding? Yes. Even if you aren't planning to sell, periodically reviewing your homeowner's insurance is worthwhile. Home values, construction costs and personal circumstances change. A policy you've carried for years may no longer reflect the cost of rebuilding your home or the coverage you actually need. An insurance professional can help identify whether you're adequately insured, potentially over-insured in certain areas, or missing coverage you assumed you had. When Is the Right Time to Sell a Home in Whatcom County? There isn't one perfect age, season or life event that tells you it's time to sell. The right time is when your finances, home, lifestyle and future plans point in the same direction. For some Whatcom County homeowners, selling creates greater financial flexibility and a simpler lifestyle. For others, staying in a familiar home and community provides greater value than moving. Neither decision is inherently better. A good real estate professional should help you understand both options, not convince you that selling is automatically the answer. Frequently Asked Questions About Staying, Selling and Right-Sizing Is downsizing always cheaper? No. Smaller homes can have lower maintenance and utility costs, but purchase price, interest rates, HOA dues, property taxes and moving expenses can offset those savings. Compare the total cost of both choices. What is the difference between downsizing and right-sizing? Downsizing focuses primarily on moving to a smaller property. Right-sizing focuses on finding a home that better fits your lifestyle, finances and future needs. That home isn't necessarily smaller. Should I get a home valuation even if I'm not ready to sell? Yes. Knowing your approximate home value and equity can be useful for retirement planning, estate planning and evaluating future housing options. Requesting a market analysis does not obligate you to sell. Can I stay in my home as I get older? Many homeowners can. The answer depends on the home's layout, accessibility, maintenance requirements, location and your financial circumstances. Sometimes relatively modest improvements can make aging in place more practical. How do I decide whether to sell my home in Whatcom County? Start by comparing your current housing costs and future maintenance needs with your estimated home equity and the actual cost of your next housing option. Then consider lifestyle factors such as accessibility, location, family and how you want to spend your time. Free Bellingham Lunch & Learn: The Real Cost of Staying in Your Home If you're thinking about these questions, I'm hosting a free educational Lunch & Learn with Nancy Leavitt of American Family Insurance : The Real Cost of Staying in Your Home And when staying is still the right call Thursday, September 17, 2026 | 1:00–2:00 p.m. 913 Lakeway Dr, Bellingham, WA We'll discuss how to evaluate staying versus right-sizing, how to understand your home's current value in the Whatcom County market, and why your homeowner's insurance deserves another look. Lunch is complimentary. Seating is limited so we can keep the group small and leave plenty of time for questions. Call or text Andi Dyer at 360.734.6479 to reserve your seat. Need Help Deciding Whether to Stay or Sell? You don't need to be ready to list your home to start planning. I can help you understand your home's potential market value, estimated equity and what comparable replacement homes are selling for around Whatcom County. From there, you can make the decision that works best for you. Andi Dyer Managing Broker, REALTOR® | Seniors Real Estate Specialist RE/MAX Whatcom County 360.734.6479 | andi@andidyer.com | andidyer.com
By Andi Dyer • July 30, 2026
Moving is hard for anyone. But for older adults, the process of leaving a long-time home carries a weight that goes far beyond boxes and logistics. It's a life event wrapped in memory, identity, and uncertainty, and it deserves to be handled with the care those things require. As a Senior Real Estate Specialist (SRES) with Andi Dyer Real Estate, I've had the privilege of walking alongside older adults and their families during some of life's most significant moments. And one of the most valuable partnerships I've built for my clients is with Jessica Lucey-Brzoza of Smooth Transitions NW Washington . Together, we cover the full picture, from the real estate side of the move to every logistical and emotional detail in between. Two Areas of Expertise, One Seamless Experience My role as an SRES means I'm trained to understand the unique needs, concerns, and goals of older adult buyers and sellers. Whether it's timing a sale around a move to a senior community, navigating the emotional complexity of selling a family home, or helping adult children coordinate from a distance, I bring specialized knowledge to every transaction. What I can't do, but what Jessica does beautifully, is manage everything that happens around the move itself. Jessica Lucey-Brzoza is a certified Senior Move Manager serving Whatcom and Skagit Counties. Her path to this work was deeply personal: after caring for her grandparents through the end of her grandfather's life, she went on to earn an interdisciplinary degree in somatic psychology: aging, death, and dying from Western Washington University, and trained as a death doula and massage therapist. She brings all of that to every client she serves: the knowledge, the compassion, the patience. "I approach each move as a unique and deeply human process," she says. "My style is rooted in listening, not pushing, meeting people where they are, honoring their agency, and helping them let go of items and spaces with care." That philosophy aligns perfectly with how I try to show up for my clients too. What Jessica Handles While I focus on the real estate transaction, Jessica coordinates the countless moving parts that make the actual move possible. Downsizing and Decluttering: Sorting through a lifetime of belongings thoughtfully and at a pace that feels manageable. Starting early means better decisions and less stress on move day. Relocation and Resettling: Establishing timelines, coordinating movers, overseeing packing and unpacking, and making sure the new home feels settled and welcoming from day one. Whole House Cleanout: When a family home needs to be cleared after a move or a loss, Jessica creates a custom plan, including working with Maxsold, an online auction platform, to help rehome items with care. Estate Dispersal Coordination: Working with families, attorneys, and trust officers to organize and distribute an estate when a loved one has passed. Helping Aging Parents Relocate: Navigating difficult family conversations and reducing anxiety for everyone involved by providing steady, experienced guidance. Why This Partnership Matters for You When an older adult is ready to sell their home, the real estate transaction is just one piece of a much larger puzzle. Clients often know they need to move, but the sheer volume of decisions and tasks involved can bring the whole process to a halt before it even begins. Having Jessica and me working together means my clients have a trusted team from the very start. I can introduce her early in the process, before the house is listed, so decluttering and downsizing happen on a timeline that works, not in a panic. And when the sale closes, Jessica's support continues, helping clients truly land in their new home rather than just arriving in it. Life isn't cookie cutter, and neither are our services. But our shared commitment to older adults in the Bellingham area means you don't have to figure this out alone. Ready to Talk? Whether you're thinking about selling, already in the process, or helping an aging parent navigate a transition, I'd love to connect, and I'm happy to introduce you to Jessica as part of that conversation. Andi Dyer Real Estate Senior Real Estate Specialist (SRES) andi@andidyer.com Smooth Transitions NW Washington Jessica Lucey-Brzoza, Senior Move Manager 360-927-3448 info@smoothtransitionsnww.com Bellingham, WA Serving Whatcom and Skagit Counties Schedule a free consultation with Jessica
By Andi Dyer • July 30, 2026
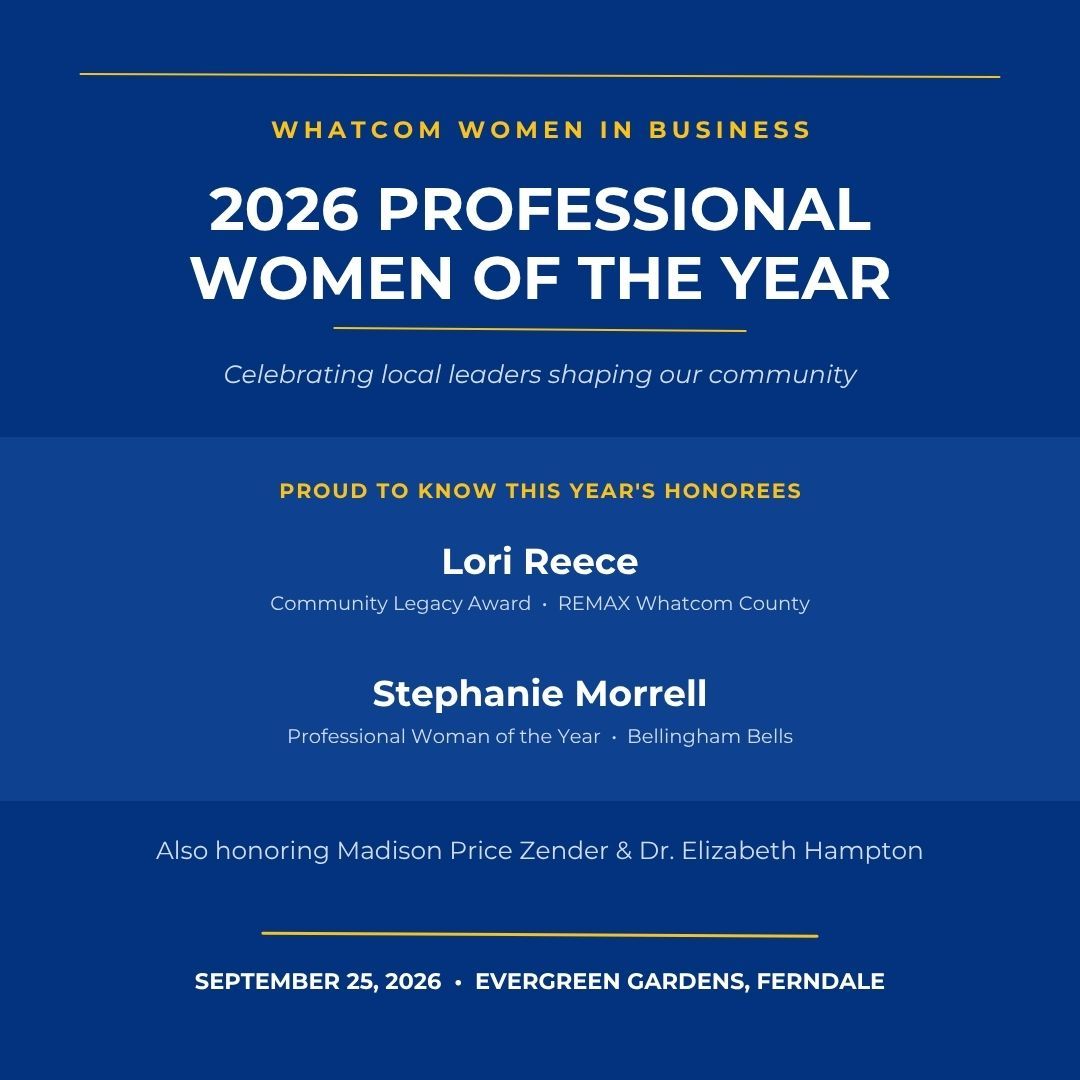
Quick answer: Whatcom Women in Business (WWiB) is honoring four local leaders at its 2026 Professional Women of the Year (PWOTY) Awards on Friday, September 25, 2026, from 5:30–8 p.m. at Evergreen Gardens in Ferndale: Stephanie Morrell (Bellingham Bells), Madison Price Zender (VSH CPAs), Dr. Elizabeth Hampton (CorePhysio), and Lori Reece (REMAX Whatcom County), who is receiving the Community Legacy Award. Tickets are available at wwib.org . Every September, WWiB honors local women whose leadership has shaped businesses and community life across Whatcom County. This year, two of the honorees are women I have the privilege of knowing personally — and their stories are worth sharing in full. Who won the 2026 Whatcom Women in Business PWOTY Awards? Four women are being recognized this year: Stephanie Morrell, Madison Price Zender, and Dr. Elizabeth Hampton as Professional Women of the Year, and Lori Reece as recipient of the Community Legacy Award. Lori Reece — Community Legacy Award Lori Reece, Broker/Owner of REMAX Whatcom County and REMAX Gateway, is receiving WWiB's Community Legacy Award this year — a distinction reserved for someone who hasn't just built a career, but shaped an entire industry. Lori founded her brokerage in 1991 with four brokers. Today it supports more than 125 real estate professionals across six offices in Northwest Washington, and she's been named RE/MAX Pacific Northwest Broker/Owner of the Year twice. Lori is my designated broker, and I see firsthand what that kind of legacy actually looks like day to day — the standard she sets, the mentorship she gives freely, and the culture she's built that so many of us in this industry get to work inside of. This award is well earned. Stephanie Morrell — Professional Woman of the Year Stephanie Morrell, President & GM of the Bellingham Bells, is being honored for a career that speaks for itself. She joined the Bells in 2013, was named the team's first female General Manager in 2016, and stepped into the President & GM role in 2024 — a tenure that has included tripling team revenue and earning two West Coast League Executive of the Year honors. I got to know Stephanie through Leadership Whatcom, and watching her lead our cohort with that same clarity, drive, and follow-through made it no surprise to see her recognized at this level. Madison Price Zender — Professional Woman of the Year Madison Price Zender is a Rising Partner at VSH CPAs, where she's built her career helping Whatcom County business owners grow and manage their finances. Her recognition reflects the trust local business owners place in her guidance year after year. Dr. Elizabeth Hampton — Professional Woman of the Year Dr. Elizabeth Hampton, a physical therapist in practice since 1987, founded CorePhysio and has led it as CEO and Clinic Director ever since, building one of the region's go-to practices for recovery and active living. Why This Matters It means something to watch people you know — people whose work ethic and character you've experienced up close — be recognized publicly for exactly those qualities. If you've crossed paths with Lori, Stephanie, Madison, or Dr. Hampton through real estate, the Bells, Leadership Whatcom, VSH CPAs, CorePhysio, or anywhere else in this community, I'd encourage you to join in celebrating them this September. Event details: Whatcom Women in Business — 2026 Professional Women of the Year Awards Friday, September 25, 2026, 5:30–8 p.m. Evergreen Gardens, Ferndale Tickets and sponsorship: wwib.org Proceeds support WWiB's mission of advancing women in business across Whatcom County, including its scholarship program for local women pursuing higher education. Source: WhatcomTalk, "Whatcom Women in Business to Honor Four Local Leaders at 2026 Professional Women of the Year Awards" About the Author Andi Dyer is a real estate agent with REMAX Whatcom County, serving buyers and sellers across Bellingham, Ferndale, and greater Whatcom County. Have a real estate question or thinking about your next move? Reach out at andi (at) andidyer.com. REMAX Whatcom County | Equal Housing Opportunity
By Andi Dyer • June 30, 2026
 A Whatcom County real estate story about persistence, creativity, and one very magical piece of land Some clients come to me with a clear picture of what they want. This client was one of them — and what he wanted wasn't a bigger kitchen or a better commute. He wanted land. He was living in a 4-bedroom condo in Sumas. Nice place, honestly — vaulted ceilings, large windows, over 1,500 square feet. By most standards, a great home. But he was done with condo life. He missed having dirt between his fingers. He wanted space for his grandkids to run around, somewhere to store his boat and kayak, and the kind of quiet that doesn't exist when you share walls. So we started looking. We Found Something Magical It didn't take long to find the right property — a piece of land on California Trail that stopped us both in our tracks. It borders a slough. Most people drive right past that slough without a second thought, but if you know what to look for, you know how rare it is. Eagles fish there — not occasionally, but regularly. You can watch them pluck salmon right out of the water. Herons show up every single day. The property backs up to a park and has only one neighbor. It's the kind of place that makes you exhale the moment you step onto it. This was the one. The Catch Here's where it got complicated. To make an offer on the California Trail property, my client needed to sell his Sumas condo first. He couldn't carry two properties, so we'd have to make the offer contingent on the condo sale. That's a real ask of any seller — essentially saying, "We want this property, but only if everything else goes right first." We got the contingency accepted. Now we just had to sell the condo. Sumas is not the fastest-moving market in Whatcom County. We knew going in that we'd need to be strategic. We priced it competitively and started hosting open houses. Then the atmospheric flooding hit. If you were in Whatcom County during those events, you know how bad it was. Most of Sumas was underwater. And even after the waters receded, the psychological damage to the market lasted much longer. Buyers were scared. The words "Sumas" and "flooding" were now permanently linked in people's minds, and that fear was showing up at every showing — or rather, in the absence of showings. A Problem Stacked on a Problem The other challenge: the condo's price point was squarely in first-time homebuyer territory. That's not a bad thing — first-time buyers are motivated, they're excited, they want to own. But many of them hit the same wall: they don't have enough for a down payment. This is where I was able to do something most agents can't. I'm certified by the Washington State Housing Finance Commission to teach the First Time Homebuyer Class. Completing that class is one of the requirements to qualify for down payment assistance programs — and there are real programs in Washington that can provide thousands of dollars in free down payment funds to qualifying buyers. So I set up multiple classes. The goal was to get interested buyers educated, certified, and funded so that the down payment barrier was no longer a reason they couldn't buy. We kept hosting open houses. We kept promoting. But the condo sat. The Fire Sale With two weeks left on our contingency deadline, I knew we needed to do something drastic. We launched what I called a Fire Sale — and we told the whole story publicly. Not just "price reduced" and a Zillow listing. We got loud. We shared the situation, the timeline, the stakes. People responded to the honesty. The post got attention. Buyers who had been watching from the sidelines started paying attention. On the last possible day of our contingency window, we got an offer. The Win He sold his condo. He bought his dream property on California Trail. And somewhere on that land right now, his grandkids are running through the grass while eagles fish the slough. This is why I love this job. It's not always a straight line. Sometimes it's flooding and fire sales and homebuyer certification classes and open houses that feel like they're going nowhere. But when you stay creative, stay committed, and keep believing in the right outcome for your client — it comes together. Thinking About Making a Move in Whatcom County? Whether you're trying to sell in a tough market, navigating a contingency situation, or you're a first-time buyer who needs help understanding your options — I'd love to talk. I specialize in finding creative solutions for clients who have complex situations, and I'm one of the few agents in Whatcom County certified to teach the First Time Homebuyer Class so buyers can access free down payment assistance. Reach out anytime. Let's figure out what's possible. Andi Dyer | REMAX | Whatcom County Real Estate andi (at) andidyer.com
By Andi Dyer • June 18, 2026
The body content of your post goes here. To edit this text, click on it and delete this default text and start typing your own or paste your own from a different source.
By Andi Dyer • June 6, 2026
Receiving multiple offers is the scenario most sellers hope for — and it's more stressful than many expect. When you have two, three, or more offers in front of you, the decision feels high-stakes in both directions. Accept the wrong one and you may regret it. Overthink it and you may lose the best buyer you had. The sellers who navigate multiple offer situations most confidently are the ones who evaluate offers against a clear framework rather than a gut feeling — and who understand that the highest price isn't always the strongest offer. What's Really Going On in a Multiple Offer Situation Multiple offers typically arrive in one of two ways. Either the home generated enough early interest that several buyers submitted independently within a similar timeframe, or the seller — often with their agent's guidance — set a deadline and invited all interested parties to submit their best offer by a specific date and time. Both situations are genuine multiple offer scenarios, but they feel different. Organic multiple offers often arrive with varying terms and timelines, requiring the seller to evaluate offers that weren't designed to compete directly with each other. Deadline-driven multiple offers are more structured — buyers know they're competing and typically submit stronger terms than they would in a one-on-one negotiation. In either case, the seller's job is the same: evaluate what's actually on the table, understand the tradeoffs between offers, and make a decision they can feel confident in — not just on price, but on the full picture of each offer. What This Looks Like in Bellingham and Whatcom County In the current Bellingham market, multiple offer situations are most common for well-priced, well-prepared homes in active price ranges — particularly move-in ready homes in the $650,000–$800,000 range and accurately priced homes in neighborhoods with consistent buyer demand like Barkley, Fairhaven, and established areas near amenities. In smaller Whatcom County communities, multiple offers are less frequent but not unusual for homes that are genuinely well-positioned. When they do occur in markets like Lynden or Ferndale, the offers are sometimes fewer in number but can be equally competitive in terms. Understanding the local context — how common multiple offers are in your specific price range and neighborhood right now — helps calibrate expectations and strategy before offers arrive. The Framework for Evaluating Offers Price is the most visible component of any offer, but it's not the only one that matters — and in some cases it's not even the most important one. Net proceeds matter more than gross price. An offer at $720,000 with the buyer requesting $10,000 in closing cost assistance produces the same net as an offer at $710,000 with no concessions. Evaluating offers on a net basis rather than a headline price basis gives you a clearer picture of what each offer is actually worth. Financing strength is a critical variable. A buyer with a large down payment and a fully underwritten pre-approval is a meaningfully lower risk than one with a minimum down payment and a standard pre-qualification letter. Cash offers carry the least financing risk of all. In a multiple offer situation, financing strength is often what separates offers that look similar on price. Contingencies affect certainty. An offer with an inspection contingency, a financing contingency, and an appraisal contingency gives the buyer multiple exit ramps. An offer that waives the appraisal contingency — meaning the buyer will cover any gap between the appraised value and the purchase price — removes one of the most common sources of post-contract complications. Understanding what each offer's contingency structure means for the transaction's likelihood of closing successfully is part of a complete evaluation. Closing timeline matters for sellers who have specific needs on their end. A buyer who can close in twenty-one days may be more or less valuable to you than one offering forty-five days, depending on your situation. Sellers who need time to find their next home often find more value in a longer closing or a rent-back offer than in a marginally higher price with a compressed timeline. When the Decision Is Genuinely Difficult Sometimes two offers are close enough in every meaningful dimension that there's no obvious right answer. In those cases, it's reasonable to go back to the top one or two buyers and ask for their highest and best — giving them one opportunity to improve their offer knowing they're in competition. This should be done carefully and consistently — the same communication to each buyer, with the same deadline. Handled well, it can improve the terms of the best offer. Handled poorly, it can feel like a shakedown to buyers who submitted strong offers in good faith, and it occasionally causes the best buyer to withdraw. It's also worth remembering that no evaluation framework eliminates uncertainty entirely. Real estate transactions involve people, and people's circumstances change. The strongest offer on paper can still fall apart if the buyer's financing changes, their inspection concerns are serious, or their life situation shifts mid-transaction. The goal of thorough offer evaluation is to reduce that risk — not to eliminate it. What I Advise Clients When multiple offers arrive, I create a side-by-side comparison that shows each offer's key terms in a consistent format — net price after concessions, down payment and financing type, contingencies, proposed closing date, and any other terms that affect the seller's situation. That comparison takes the emotion out of the evaluation and makes the tradeoffs visible. Sellers who can see the offers laid out clearly alongside each other almost always reach a confident decision faster than those who are trying to hold multiple offer documents in their heads simultaneously. I also help sellers think through their specific priorities before the offers arrive if possible. What matters most to you — the highest net, the most certain close, the most flexible timeline? Knowing your priorities in advance makes the evaluation faster and the decision cleaner. Why Planning and Timing Matter Multiple offer situations reward sellers who have done their pricing and preparation work thoroughly. A home that is accurately priced and well-presented is more likely to generate the kind of early, concentrated interest that produces multiple offers. And a seller who understands their market clearly is better positioned to evaluate those offers confidently — knowing whether the offers on the table are genuinely strong or merely the best of a weak field. The preparation that produced the multiple offer situation is also what gives the seller the confidence to evaluate and decide without second-guessing. A seller who knows their home is well-priced and well-prepared approaches the decision from a position of strength rather than anxiety. The Bottom Line Evaluating multiple offers without regret requires looking beyond the headline price to the full picture of each offer — net proceeds, financing strength, contingency structure, and closing timeline. The highest price isn't always the strongest offer, and the strongest offer isn't always the most obvious one. Sellers who approach this moment with a clear framework and a good understanding of their own priorities consistently make decisions they feel confident in — not because the outcome is guaranteed, but because the decision was made thoughtfully. If you're trying to balance patience with smart action, start here: 👉 Start with a low-pressure home value and seller planning tool: https://www.andidyerrealestate.com/seller/valuation/ About the Author Andi Dyer is a Bellingham-based real estate broker with REMAX Whatcom County, specializing in helping longtime homeowners and sellers make confident, well-informed decisions. With a calm, data-driven approach and strong negotiation expertise, Andi focuses on protecting equity, reducing stress, and guiding sellers through the process with clarity and care. 📍 Serving Bellingham and all of Whatcom County 📞 Call or text: 360 • 734 • 6479 📧 Email: andi [at] andidyer [dot] com Zillow · Realtor.com · Homes.com · Google Business · Facebook · Instagram
By Andi Dyer • May 24, 2026
Every so often I work with a seller whose situation does not fit neatly into the usual real estate conversation. This was one of those. The home had been in the family for years. His in-laws had built their life there — raised children, hosted holidays, made memories that mattered. But they were gone now, and the house sat empty, quietly accumulating costs. Taxes. Utilities. Maintenance that kept getting pushed back. A roof that was not going to wait forever. What had once felt like a gift had slowly become something else: a financial obligation with no clear end date. He was not in crisis. He was not in a rush. He simply wanted someone to sit down with him, look at the real numbers, and tell him honestly what his options were. That is what we did. 
By Andi Dyer • May 15, 2026
The body content of your post goes here. To edit this text, click on it and delete this default text and start typing your own or paste your own from a different source.
By Andi Dyer • May 13, 2026
For longtime homeowners in Bellingham and Whatcom County — particularly those who bought their home in the 1990s or early 2000s — the single most significant financial question at the point of sale is usually some version of "how much of this is taxable?" Equity accumulated over twenty or thirty years in a Pacific Northwest market that has seen sustained appreciation can easily be several hundred thousand dollars, sometimes substantially more. That gain is not automatically tax-free, but most of it, for most homeowners, is. Understanding how that works — clearly, without the jargon, and with the specifics that actually matter — is one of the most valuable things a seller can do well before listing. The short version is that the federal tax code allows a homeowner to exclude up to $250,000 of capital gain from the sale of a primary residence if filing as a single taxpayer, or up to $500,000 if married filing jointly. Gains above those amounts are taxed as long-term capital gains at the applicable federal rate, with no Washington State income tax to add to the federal bill. The exclusion applies if the homeowner has owned and used the home as their primary residence for at least two of the last five years before the sale. That's the core rule. The nuance, and the places where longtime homeowners sometimes run into surprise, is in the edges of that rule rather than the center. What "capital gain" actually means for a home Capital gain, in the context of a home sale, is not the full sale price. It's the difference between what you sell the home for — net of selling costs — and what you paid for it, adjusted for certain improvements you've made over the years. The formal term for your adjusted purchase price is your "basis" or "cost basis." If you bought your home in 1998 for $180,000, added a $40,000 addition in 2006, and sell it in 2026 for $750,000 with $45,000 in selling costs, your gain is not $570,000. It's roughly $485,000 — the sale price minus the selling costs minus the original purchase price minus the improvement. This matters because $485,000 of gain for a married couple is fully within the $500,000 exclusion. Zero federal capital gains tax owed. For a single homeowner in the same situation, $485,000 of gain is $235,000 above the $250,000 exclusion, taxed at long-term capital gains rates — meaningful, but still dramatically less than the gross numbers would suggest. Getting the basis right is therefore one of the most underappreciated parts of preparing for a sale. Every significant improvement made over the years — additions, new roof, kitchen remodel, new windows, hardscaping, HVAC replacement — can add to basis if it's a true improvement rather than a repair. Repainting a wall doesn't add to basis. Replacing the whole roof does. For homeowners who have been in a home for a long time, reconstructing this history before sale can shift the tax picture by tens of thousands of dollars. The ownership and use tests The exclusion applies if you've owned and used the home as your primary residence for at least two years out of the last five years before sale. The two years don't have to be consecutive, and they don't have to be the most recent two. This matters for a few specific situations. A homeowner who moved out of their home and rented it for a year before selling can still claim the full exclusion, as long as they meet the two-out-of-five rule. A homeowner who owns two homes and is deciding which to sell may have flexibility around which qualifies as "primary" based on the facts of how the homes were used. A homeowner who converted a home from rental to primary residence (or vice versa) has a more complicated calculation that depends on the percentages of time in each use. For most Bellingham homeowners selling their long-term primary residence, the test is straightforwardly met and isn't something to worry about. But for homeowners with more complex property histories, the details matter and deserve specific attention. The frequency limitation A homeowner can only claim the full exclusion once every two years. This rarely affects retirees and longtime homeowners — most are selling a home they've been in for decades. But for sellers who have recently used the exclusion on a prior home (within the last twenty-four months), the exclusion may not be available for the current sale. Gains above the exclusion For longtime Bellingham homeowners with substantial equity, it's increasingly common for the taxable gain after the exclusion to be non-trivial. A married couple selling a home purchased thirty years ago with a current gain of $700,000 has $200,000 of gain above the exclusion, taxed at long-term capital gains rates. At the federal long-term capital gains rate applicable to many retirees (15% for the typical tier, 20% for the highest), that's $30,000–$40,000 of federal tax. Significant, but a much smaller bite than the same gain would produce if all of it were taxable. For single filers, or widowed spouses who have lost the joint filing eligibility, the math tightens quickly. A widowed spouse who sells within two years of the spouse's death can still use the $500,000 exclusion under a specific provision of the tax code. After that two-year window, only the $250,000 single-filer exclusion is available. This is one of the situations where timing, within a planning horizon, can make a meaningful financial difference. What increases and doesn't increase basis Improvements — substantial work that adds value, prolongs useful life, or adapts the property to new uses — add to basis. A new roof, a new furnace, an addition, a finished basement, a new deck, a new driveway, new windows, major plumbing replumbing, electrical panel upgrades, kitchen and bathroom remodels — all add to basis. Repairs and routine maintenance do not. Fixing a leaky faucet, repainting the exterior, replacing a few broken shingles, routine furnace service — these don't add to basis, even though they keep the home in good condition. The distinction between "improvement" and "repair" is sometimes fuzzy, and the IRS has guidance on it. Work that restores the home to its prior condition is usually a repair. Work that upgrades the home to a better condition is usually an improvement. Selling costs — the real estate commission, title and escrow fees, recording fees, and certain other closing costs — are subtracted from the sale price when calculating the gain, effectively reducing the taxable amount. This is why net proceeds matter more than gross sale price for tax purposes. Records matter more than people expect The single most common regret among longtime homeowners at the point of sale is not having records of improvements made over the years. Receipts from a 2004 kitchen remodel, invoices from a 2011 roof replacement, contractor records from a 2015 addition — these matter directly to the gain calculation, and reconstructing them after the fact can be time-consuming or impossible. If a sale is within a one to three year horizon, beginning to gather these records is one of the quieter but most valuable preparation tasks. Even approximate records supported by dated photos, canceled checks, or contractor names can help substantiate improvements on a tax return. The IRS generally accepts reasonable substantiation; it does not require perfection. Washington State specifics Washington does not have a state income tax, which means there is no state capital gains tax on the sale of a primary residence for the overwhelming majority of sellers. (Washington does have a capital gains tax on long-term gains from certain financial assets above a threshold, but that tax specifically excludes real estate sales.) Washington does have a real estate excise tax (REET) paid at the time of sale, which is effectively a transfer tax rather than an income tax. REET is paid out of the sale proceeds at closing and is separate from capital gains. For most Bellingham sellers, the tax analysis is therefore a federal-only analysis, which simplifies things considerably compared to states with income taxes stacked on top. What this actually means for planning For most longtime Bellingham homeowners selling a primary residence, the combination of the $250,000 / $500,000 exclusion, proper basis documentation, and the absence of state income tax means that the majority of the gain is likely to be tax-free, and the portion that is taxable is taxed at long-term capital gains rates rather than ordinary income rates. That's often a more favorable picture than sellers initially expect. The places where this can go sideways are: insufficient basis documentation that leaves money on the table; widowhood situations where the two-year window for the $500,000 exclusion has closed; rental-to-primary conversions that complicate the calculation; and sales within two years of a previous primary residence sale where the exclusion isn't available. Each of these deserves a specific conversation with a CPA or tax advisor in advance of listing. A quieter way to think about this The tax picture of a home sale is rarely as punishing as longtime homeowners fear. For a very large portion of Bellingham sellers, the exclusion covers the entire gain, and the sale is federally tax-free. For sellers with gains above the exclusion, the tax is real but manageable and usually represents a small percentage of the total equity being realized. The work worth doing in advance is gathering records, confirming the basis, and having a brief conversation with a tax professional to verify the specifics for your situation. That work produces a clear number rather than a vague worry, and a clear number is almost always easier to plan around. Frequently asked questions Do I owe capital gains tax if I reinvest the money into another home? Not because of the reinvestment itself. The old "rollover" rule that required buying another home to defer tax was replaced by the current exclusion system in 1997. The exclusion applies whether or not you buy another home. What about a 1031 exchange? A 1031 exchange applies only to investment property, not to a primary residence. For a home you've lived in as your primary residence, the exclusion is the applicable rule, not a 1031 exchange. Do I need to report the sale if the entire gain is excluded? Generally not, if you receive Form 1099-S from the closing agent and the entire gain qualifies for exclusion. If the gain exceeds the exclusion or if you don't meet the ownership and use tests, the sale must be reported. Your CPA can confirm which applies. How are selling costs handled? Commissions, closing costs paid by the seller, and certain other costs reduce the sale price for purposes of calculating the gain. They are not separately deductible; they're netted into the gain calculation. Related reading  *What Longtime Homeowners Often Get Wrong About Their Home's 'Basis'* goes deeper into basis calculation, and *How Long-Term Equity Changes the Math on Whether to Sell or Hold* addresses how the equity picture affects broader planning decisions.
More Posts